10.07.26
Webinar | GMA Trucking Education Workshop 1
In this first session of GMA Trucking’s carrier education series, recorded on October 6, 2026, the GMA team explains how book and claim works, how it fits into greenhouse gas accounting, and how pairing it with demand aggregation can help carriers get more zero-emission heavy-duty trucks on the road.
A full transcript of the webinar is available below. Presentation slides can be accessed here.
The following transcript has been edited for legibility and clarity.
ANDRE DE FONTAINE:
Okay. Good morning, good afternoon to everybody. Thank you for joining us today for a webinar that GMA Trucking is hosting to give a little bit of background on book and claim and share some plans for future work. Jakob, if you could go to the next slide. Thank you.
So why are we doing this? We have set up a series of workshops, one-hour webinars, over the course of the next couple of months. As I think many of you know, GMA Trucking has been working on book and claim for zero-emission trucks along with our partners. We ran an RFP last year and had a successful pilot project, but we’re looking to grow and scale that effort. As part of that, we want to make sure that the community of carriers and the business partners you work with understand the system, have knowledge about it, and are prepared to participate when we launch our next procurement, which will be in 2027 — so next year. We’re running these workshops with that goal in mind.
Today is really about the basics: a 101 on book and claim and some accounting. Then we’re going to get progressively more specific in future workshops, covering accounting, claiming, additionality, et cetera, in more depth.
For today, as you can see on the agenda on screen, I will spend a few minutes teeing up the issues. I’ll then pass it over to my colleague Jakob, who will cover some accounting and the basics of book and claim, both in general and as it applies to this sector. Clayton will discuss the business case and the benefits this model can bring, especially when it’s combined with demand aggregation, which is what we also do. We’ll have a short discussion about next steps, and then we will open it up to Q&A. If things go well, we should have about 15 minutes of Q&A to answer any questions you might have.
Please drop your questions in the chat — that’s probably the most efficient way of getting them. We’ll hold the questions until the end to make sure we can get through all the content. If we end up with more questions than we can answer today, we have these future webinars coming up over the next couple of months, and we’ll make sure to answer whatever we weren’t able to get to then.
So, the team with me today. First of all — I should have probably done this at the beginning — my name is Andre de Fontaine. I’m a managing director at GMA, where I have the privilege of working with the rest of the team on our trucking program. A lot of that is led by Clayton Gerber, our senior manager, supported by Jakob Sanchez and Stacy McCluskey.
While she is not on the call today, Illina from the Smart Freight Centre has been a great partner throughout all of this, and you’ll definitely be seeing more of her in future webinars. She’s on a well-deserved holiday. In general, we’re working very closely with SFC to understand a number of different things, but especially how book and claim can be integrated into physical demand aggregation through efforts they’ve stood up, like ZET SCALE, which I’m sure many of you are aware of.
Let me give a little bit of background on GMA. I’m going to move through this quickly, because I think we’re all eager to get into the guts of the presentation.
Briefly, GMA — the Center for Green Market Activation — has been around for a couple of years, so we’re a relatively new NGO. We are focused on market-based and demand-side measures to decarbonize the hard-to-abate sectors, and you can see the sectors we’re active in running along the top. These are your traditional hard-to-abate sectors.
We go about this work in a couple of different ways that are complementary to one another. We design and build book and claim systems, often working with partners, often building on existing work, and sometimes building things relatively from scratch. But we are always borrowing lessons learned from the other sectors we operate in, to make sure there’s a consistent structure to this work and for efficiency gains.
We usually do the demand aggregation after the system is built, once we have a functioning book and claim system. Through this, we work with a group of committed buyers — this is what we did with GMA Trucking last year. We form a buyers alliance, and we run a competitive procurement process on their behalf. The idea is to send a larger demand signal to the market to help scale these technologies faster than if we were to rely on individual bilateral negotiations.
An important differentiator for GMA is that we run this process all the way through to contracting. We want to make sure that binding contracts are signed for the attributes so that the investments really do occur.
You can go to the next slide, Jakob.
I’m fairly certain that everybody on the call recognizes the imperative behind the work we all do. It is really important to get more electric trucks on the road as quickly as possible if we are to stay on track for long-term decarbonization objectives. The IEA says we need a little more than a third of all heavy-duty truck sales to be zero-emission by 2035 — less than 10 years away — if we want to stay on track for the 2050 goal.
At the moment, we are not really on track. In the US in particular, which is a major market for heavy-duty trucks, only about three-tenths of 1% of new heavy-duty truck sales are zero-emission. There’s reason to be optimistic that the curve will accelerate, but the current situation is still pretty minimal.
At GMA, we are focused primarily on heavy-duty trucks. All of the road freight sector — really, all of the road transport sector — needs to electrify, but we launched this program specifically to tackle heavy-duty trucks for two reasons. First, they are the hardest to decarbonize, and I think they need the most help. Second, you get the biggest bang for the buck. Heavy-duty trucks are a little less than 10% of the total US truck fleet, but they are responsible for close to half of all the emissions. So you can get some really significant emission savings by replacing a relatively small portion of those trucks.
When you do so, the benefits are significant and cut across a number of different categories. The emissions benefits are clear from what we just talked about, but you also have lower energy costs and lower maintenance needs. This is what allows these trucks to eventually reach cost parity.
In addition to the greenhouse gas emission savings, you also get reductions in localized air pollution, which improves public health, especially in communities that are already exposed to a lot of air pollution. Then, of course, there are the energy security benefits of reducing reliance on fossil fuels. And something we hear time and time again is that drivers just like these vehicles better. They’re new, it’s a smoother ride, it’s quieter. There are a lot of reasons to like these trucks. So the benefits are very real.
If you go to the next slide — they are being realized today, but not in a way that’s well distributed. We’re seeing great variance in the penetration rates of zero-emission heavy-duty trucks. China is really zooming ahead with transitioning its fleets to electric. The same cannot currently be said of the European Union and the United States.
When you look at the US, there’s a lot of unevenness across states, and it should be no surprise that the states with the most significant public incentives currently have, by far, the largest share of deployments, with California far and away the biggest concentration of electric heavy-duty trucks. So we think this is an opportunity for all of us, working together, to deploy more trucks in more locations across the country.
So that’s a little bit of background on where we are and where we hope to go. At this point, I’m going to turn it over to Jakob to talk more about book and claim and accounting.
JAKOB SANCHEZ:
Thank you, Andre.
Before diving into some of the accounting details, I think it would be really useful to zoom back out and look at the levers we have as a market to reach our ultimate end goals.
Historically, policy and incentive structures have helped overcome a lot of the early adoption barriers that much of the sustainability world faces. For trucking in particular, this has come in the form of California’s HVIP program, the Western Seaboard’s Low Carbon Fuel Standards, and utility make-ready electrification programs. These can be very supportive, but policy support is not uniform across the country, and it is also subject to change over time.
Looking ahead, we want to arrive at cost competitiveness. This is where the business case for low- and zero-emission vehicles really stands on its own merits. That could be supported through next-generation technology, such as the new Tesla Semi; reduced on-peak electricity prices; expanded access to reliable and accessible charging infrastructure; and better financing terms as leasing partners mature and start to realize the long-term value of these electric cabs.
Coming back to that middle column, corporate demand, we see this as really being the bridge between policy support, which can be quite supportive, and the ultimate end state, which is cost parity, where these trucks really speak for themselves. This is an arc that will be very familiar from so many sustainable technologies, just as it was for solar and wind. Those technologies were supported by policy until the market grew enough and advances in technology allowed them to stand on their own economics.
That middle column is really where GMA focuses its work, and it’s the lever we’re able to activate today. The intent is not for corporate demand to replace supportive public policy or fix every element of the business case, but rather to provide a source of support that companies can act on today.
Corporate buyers already purchase freight services and are quantifying portions of their transportation emissions. As a function of that, they are setting goals that increasingly include the broader parts of their value chain. If that existing demand can be translated into stronger commercial commitments, it can give carriers and the market more confidence around the revenue side of the electric truck investment.
Corporate sustainability commitments quite frequently come in the form of SBTi commitments — the Science Based Targets initiative, which I’ll touch on more later — but also other initiatives, such as the UN’s Race to Zero campaign, and the work we do here at GMA through demand aggregation.
This is especially important because a carrier is being asked to make a long-term investment in a truck and potentially charging infrastructure, while historically, freight contracts and individual shipper relationships can be much shorter-lived or less predictable. So we see corporate demand as the main vector through which we can channel investment toward these decarbonization goals.
To understand why corporates have these goals in the first place, it’s important to step back a layer and understand what corporate greenhouse gas accounting is and what it even means.
Perhaps the most widely cited and used global standard for greenhouse gas accounting is from the Greenhouse Gas Protocol. It introduced scoped accounting, whereby an organization can organize its emissions into buckets known as Scope 1, 2, and 3. This allows companies to baseline where their emissions are, identify hotspots, set goals, and track progress toward them.
In the context of trucking, emissions from freight and logistics are often a very significant and challenging source of emissions to address, because of how far removed they can be from a corporate’s actual control. If a company isn’t actually paying for the freight, or isn’t the one contracting for it directly, these can be really nebulous relationships to manage. This helps explain why corporates have a hard time addressing these emissions, and also the role we have to play.
If we look at the diagram on the right, this is pulled from the GHG Protocol. The GHG Protocol Corporate Accounting and Reporting Standard, as I said, is the most widely used and referenced corporate accounting standard globally. It serves as the foundation for how companies measure and report on these different scopes.
Scope 1 includes everything within your direct operational control: stationary combustion, such as natural gas or oil burned in boilers, furnaces, and generators; mobile combustion, meaning fuel used in a company-owned vehicle, aircraft, or vessel; and other emissions, such as process and fugitive emissions from chemical reactions or refrigerant or methane leaks. That all goes into your Scope 1. Importantly, your Scope 1 is also somebody else’s Scope 3, and Scope 3 makes up the entirety of the rest of a corporate’s value chain.
Scope 2 covers emissions from the generation of purchased electricity, steam, heating, or cooling that the company consumes. This is where the electricity purchased to run our battery electric trucks comes in.
And then Scope 3 is the giant monster that covers the rest of the accounting process.
When thinking about greenhouse gas accounting, it’s important to understand that these are ultimately tools. The purpose of accounting is to give us the ability to prioritize action, track against baselines, and communicate our results in ways that are reliable, defensible, and standardized.
As I mentioned, because Scope 3 encompasses so many components of a value chain — from the purchase of capital goods, business travel, and waste generated in operations, to the processing of your products, how those products are actually used, and their disposal and end-of-life treatment — it can be quite a lot for a corporate to address. And because corporates are setting these goals, we are seeing growing demand for solutions that can help them advance their sustainability objectives.
For freight in particular, emissions appear in three major places. For carriers, this is Scope 1 mobile combustion. Importantly, the GHG Protocol defines your Scope 1 as anything over which you have operational or financial control, so if a carrier leases trucks, those would also fall into its Scope 1 emissions.
For Scope 3, freight falls into either Category 4, upstream transportation and distribution — the transportation and distribution of goods that the company has itself purchased and paid for — or Category 9, downstream transportation and distribution, which is everything that happens after the point of sale that the reporting company does not pay for.
As you can imagine, Category 9 in particular can be very challenging for a corporate to address, because they don’t have direct financial insight into it. This is why it’s so important to begin these conversations throughout your value chain now: so we can start to provide greater visibility into data, improve its fidelity, and grease the wheels of those relationships so that companies can begin tracking those emissions reliably and set goals against them. And the point of setting goals and targets is so we can ultimately reach our planetary goals of near-term and net-zero targets.
As I mentioned earlier, SBTi, the Science Based Targets initiative, is the main target-setting and validation body. SBTi provides independent review and validates whether a company’s emissions reduction targets are ambitious enough to support global climate objectives. As a result, any SBTi-approved target is viewed as a credible signal that the company has a serious and measurable decarbonization plan.
SBTi targets have become an important benchmark for customers, investors, suppliers, and internal sustainability teams. Many large companies are now expected to have science-based targets and to have begun engaging their suppliers to measure emissions and demonstrate a meaningful pathway to reduce them.
So for companies with significant freight emissions, SBTi targets create pressure to find practical ways to reduce Scope 3 emissions. That’s one of the reasons there’s growing interest in zero-emission trucking, low-carbon freight programs, and book and claim more broadly.
From this graphic, we can see that a pretty large proportion of companies have validated targets under SBTi, and more than 70% of those include Scope 3 within their targets. To put the scale of the demand into perspective, as much as 75% of a corporate’s emissions can come from Scope 3. So it really is a huge component of corporate inventories, and companies are looking for meaningful ways to address it.
Historically, though, freight and trucking in particular has been a very fragmented ecosystem. A shipper who is motivated and willing to support zero-emission trucks might not be in a geography or on a route, or have carriers within its network, that can support battery electric deployment.
Of course, direct matching can work really well when it works, and we need more of it. But if there’s insufficient infrastructure, if electricity costs aren’t low enough, and if carriers can’t source enough volume to hit critical utilization thresholds, the economics start to become more challenging.
In this example, Shipper 1, who is interested but can’t find suitable carriers in its network, is forced to use a traditional diesel trucking service despite its intentions. Meanwhile, a carrier who has already made the initial investment and deployed a zero-emission vehicle might not have shippers in its network willing to help cover some of the additional costs arising from capital expenditures, infrastructure deployment, and so on. This is exactly the problem book and claim was invented to solve.
So if we revisit that example, here’s a brief overview of what book and claim is. It is the process by which the environmental attributes of a service — in this case, Carrier A’s battery electric truck service — are decoupled from the actual freight and sold to a shipper as an environmental attribute certificate, or EAC.
Shipper 1, who was motivated to support electric trucks but didn’t have any in its network, pays the green premium to the carrier, and in return receives the EAC. So even though its freight was physically moved by Carrier B using a traditional diesel truck, Shipper 1 can take that environmental attribute certificate, claim it against its Scope 3 inventory, and take the road transport emissions reductions. Meanwhile, Shipper 2, who was uninterested in or unmotivated to purchase the battery electric trucking service, simply receives a default diesel truck emission factor.
The process by which the environmental attribute is decoupled and then sold is book and claim. It’s the mechanism through which a lot of catalytic demand for Scope 3 decarbonization solutions is channeled from motivated shippers and buyers who have set ambitious climate goals.
So we’ve briefly covered the role of the carrier in deploying the electric vehicle and generating the EAC, and the role and motivations of shippers in purchasing those EACs to abate their Scope 3 emissions. I’m now going to focus a bit on the middle category: the CPOs, or charge point operators.
For our first procurement, we required that CPOs purchase renewable energy to match the electricity consumption of the electric vehicles one to one. We did this because we want to push the market toward being as sustainable and decarbonized as it can be, and we thought this would be a useful tool to help propel that objective forward.
It’s important to note that market-based accounting for electricity is still evolving, especially for freight and the allocation of electricity attributes. Additional guidance is needed on how different actors should account for and disclose within Scope 2. That will be forthcoming, and it’s something we can touch on in greater detail in the following webinars.
But in many cases, CPOs will play a really important role in providing charging data and electricity sourcing information. Again, we would encourage all involved parties to begin these conversations sooner rather than later so we can start forging those relationships.
This is the ecosystem as it stands, and around all of that activity is where we sit here at GMA. We help design the book and claim system, we identify willing carrier partners, we convene a buyers alliance of member shippers interested in procuring zero-emission trucking attributes, and we facilitate the bilateral contracting between the parties.
To walk through this in greater detail and really dive into the specifics of what GMA Trucking does, I’m going to hand it over to Clayton Gerber.
CLAYTON GERBER:
Awesome. Thanks, Jakob.
Continuing where Jakob left off, he mentioned a bit about the pillars and key activities of GMA Trucking. I’m going to take us into specifically what we do and how we see the interconnection between demand aggregation, book and claim, and the physical demand aggregation efforts we’ve been seeing in the market.
Quickly, on GMA Trucking: the program was launched roughly three years ago, bringing together a number of shippers to operationalize these different pillars — really helping to build and refine the book and claim systems, and then operationalizing them through these procurement processes. You can see some of the names of our members on the right-hand side. The membership spans tech, CPG, and several freight forwarders as well. The goal in our upcoming procurement process is to grow this number and bring in more shippers to activate more demand.
We’re also very grateful for our partnership with SFC, the Smart Freight Centre, and their expertise on a number of things, both accounting-related and fleet electrification.
I’ll note here that we don’t have many details on our first procurement in this presentation, but as was mentioned, we completed the procurement process at the end of last year. We selected the all-electric carrier Nevoya as the winner of that competitive process, finalized the contracts at the end of last year, and those trucks will be delivered this year. In the next webinars, we’ll touch more on the lessons learned and the procurement process in detail, so more to come on that.
If you go to the next slide — I want to go a layer deeper on how these two things come together. As mentioned, we bring together a number of shippers to help catalyze demand and bring it to fruition in a way that is bankable and scalable, and that also lowers cost. We see economies of scale: more trucks per charger, more utilization of those trucks. How can we grease the wheels of the system so that we can actually realize cost reductions through high utilization?
The book and claim system Jakob walked through is what provides the flexibility to bring these things together the way we do, because it enables long-term contracting. Whereas many freight logistics contracts are short-term — ranging from daily up to perhaps a year — book and claim contracts let us more flexibly sign multi-year contracts. That gives the carrier more assurance of a revenue stream and allows them to offer competitive rates and make the investment case. It’s really these two things coming together that allow us to do what we do in the way we do it.
If you go to the next slide — in this next procurement, a bit differently from the first round, we’re hoping to more intentionally bring book and claim together with physical demand. By physical demand, I mean that a shipper who is motivated to decarbonize, or to deploy electric trucks on its routes, actually has its goods on the trucks. With book and claim, it isn’t necessarily their goods on the trucks; they’re buying a certificate.
As many of you are probably aware, the ZET SCALE project was just announced a couple of weeks ago by SFC and Catalyst Mobility. ZET SCALE worked with several shippers in the market to aggregate their collective interest and demand, in order to secure lower truck pricing through a large-scale procurement of Class 8 trucks.
We are working with the SFC and Catalyst teams to bring these two things together, so that we can complement the work the ZET SCALE program has done — creating competitive leases and identifying the routes with the most favorable TCO — and then layer in book and claim. I’ll get into that in a minute, but I also want to give kudos to the team that led ZET SCALE.
Quickly, back to the book and claim side. I want to double-click on some of the benefits we see for both carriers and shippers in engaging in the book and claim market.
The first is de-risking the investments themselves. As I mentioned, multi-year contracts from creditworthy shippers provide revenue certainty to carriers making these investments, or signing contracts at a higher price — for example, if you’re leasing or using any sort of charging-as-a-service. You have assurance that there is revenue and demand in a contractual, bankable form, which helps you make the investment case to leadership as well as to finance partners.
The second is how that revenue gets used. The certificates have to be generated from moves. You can’t just buy certificates from the trucks themselves; they have to come from the truck actually being utilized, because that’s what avoids the diesel alternative. The revenue from the certificates can then help the carrier offer the most competitive rates to the market and ensure those vehicles are utilized. In particular, this can mean winning business from shippers who aren’t necessarily motivated by the greenness or electrification of the trucks — shippers who are simply price-sensitive. With this additional revenue stream, carriers can find those shippers, service their loads, utilize the trucks more, and in turn reach cost parity faster.
Third, this is a way to differentiate yourself as a carrier from the rest of the market. Book and claim can be a flexible tool to help you engage in this market and continue to scale, so that you become a front-runner in the zero-emission transition.
And lastly, this is a new kind of revenue stream and a new way of engaging with shippers. It looks a bit different, but it’s a way of being introduced to these companies.
If we go to the next slide — I want to touch on how we see these things coming together.
Physical demand is critical and important. It reflects the end state we want: companies that are motivated to have their goods physically moved on these trucks going out into the market. Having that physical demand solidified provides a form of guarantee to a carrier that there are shippers who want to prioritize the electric vehicle service. That utilization leads to lower TCO as carriers reach their investment decisions and what they expect to be parity over time.
Where we see the complication is when there isn’t sufficient utilization from the physical shipper network in a region to justify the full benefits of electrification. If a carrier is unsure whether it can reach the needed utilization with its existing shipper relationships, or from shippers motivated by electrification, there may be more empty loads and empty backhauls on those EVs. That means lower utilization than expected, which undermines the path to parity. That in turn may make the carrier less willing to deploy its next trucks, because if it hasn’t been able to utilize them to the extent expected, it isn’t reaching the payback it anticipated when it made the investment case. So without sufficient utilization, there’s a worry that in some instances carriers won’t be able to reach the revenue they need.
Obviously, this isn’t the case in all instances. We know of many cases where carriers get strong demand assurance from shippers, can match different shippers, or have a shipper with enough volume to fully utilize those electric trucks. But we also know there are other cases where the matching needed for full utilization isn’t yet known, or isn’t secure enough for a carrier to make the investment.
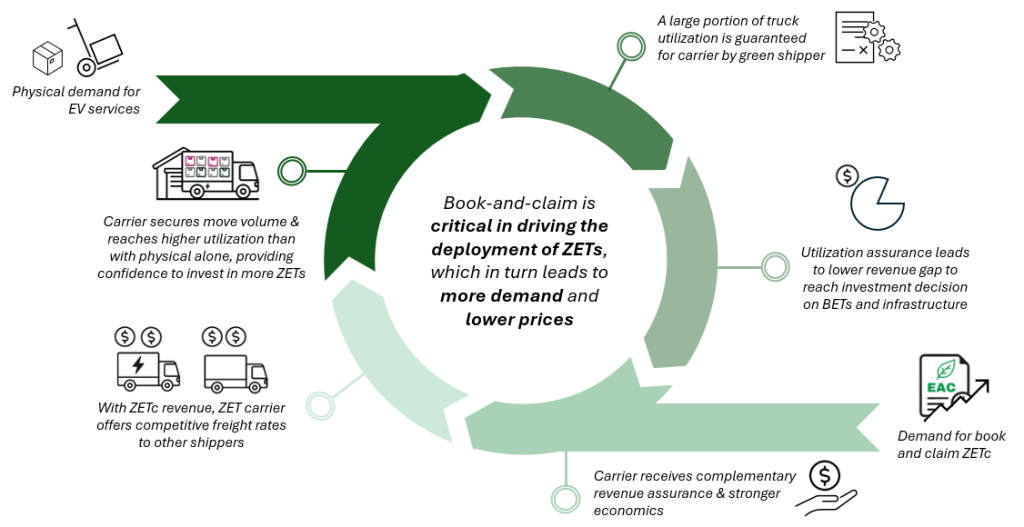
If we go to the next slide — what we see as the catalytic new element here is the injection of book and claim. If we follow this flywheel again, you have physical demand. That physical demand is an anchor that helps solidify a certain portion of a carrier’s expected utilization.
Then book and claim comes in and says, “We will help contribute an additional revenue stream.” That complementary revenue both bolsters the carrier’s economics and allows it to offer more competitive rates to the market, identifying additional shippers beyond those motivated strictly by the electric nature of the service. That leads to more utilization and, in turn, helps the carrier hit the targets it needed to make the investment case. With that, the carrier sees the market and the utilization of these trucks, has that flexibility, and makes the next investment in the next trucks.
That’s how we see this scalable flywheel and positive feedback loop, where we can actually reach the needed utilization, have flexibility from the book and claim certificate revenue, and lower overall premiums for everybody engaged in the market. This can be an interim solution on the way to where we want to be in the future: a world where everyone is deploying EVs on every route because it’s the most cost-effective thing to do. We know we’re not there today, and we need to do everything we can to get there. This is one of the solutions we see to create more flexibility in the market.
If we go to the next slide — in terms of next steps, within the next few days we are launching a Request For Information to gather information and perspectives from you all in the market to help inform the next procurement. We’re still refining the procurement model itself — the design, the reporting requirements, the commercial structure — to make sure it is tailored to where the market is.
We also want to identify opportunities: where are you looking to deploy zero-emission trucks, and how? And we want to know what questions and needs you have for this market, so we can be intentional and thoughtful and put you all in the best position to apply.
If we go to the next slide — Tactically, the RFI will come out in the next few days. We have the email addresses of everyone who registered, so we’ll send it directly to you, but it will also be broadly disseminated and posted on the GMA website. The email will include instructions on how to respond, and the due date will be the end of November. That will feed into our last webinar as well. We’ll gather as many questions and perspectives as we can, and ultimately those will be incorporated into the procurement process, which will launch in early 2027.
If you have any questions, first, put them in the chat now. We can also try to cover anything in the next webinars. And lastly, you can always reach out to any of us on the team, or at the trucking@gmacenter.org email. We’re trying to have as many avenues for questions and clarifications as possible.
Quickly, on the last slide: I know today’s meeting was relatively high-level, so for those of you already engaged in the book and claim market, it was probably largely a refresher. But we know many of you may be pretty new to this as well, so we wanted to start at a very high level: What is book and claim? What is greenhouse gas accounting? How are we using the tools at our disposal to help deploy these trucks and spur the market?
In the next two workshops, we’re going to go a couple of layers deeper. In the November workshop, we’ll talk more tactically about EAC generation: what data is needed, what the reporting requirements are, and more specifically, the roles of carriers versus CPOs and others. We’ll also share some of what we learned from executing the first pilot. The goal is to give you all the information you need to engage in this market and respond to the upcoming RFP.
In the last workshop, we’ll get more into the credibility components: how to avoid double counting and what’s needed. There are things you give up by participating, so to speak — it’s not simply a grant. So we want to be very clear about the integrity measures that need to be incorporated, as well as the contracting components. As we said at the top, what we really do is help facilitate strong contracts for these certificates, so that a carrier knows, before it needs to make these investments, that it has assurance in doing so. The goal for that last workshop is to move toward a state of readiness and to provide more space for questions and clarifications as we get into the deeper content.
With that, that concludes the main body of today’s presentation, and we’ll transition to questions and answers for the next 15 or so minutes. I’ve seen a bunch of questions come in, so please keep putting them in the chat — you may think of more as others ask theirs.
I’ll note up front that, because we have these other webinars coming, we may not go into great detail on some of the nitty-gritty accounting questions. We can touch on some of it at a high level, but there will definitely be more to come on the accounting components in particular.
So with that, Stacey, would you like to help shepherd us through the questions that have been coming in?
STACEY MCCLUSKEY:
Yes, gladly — and thank you to everyone who has submitted questions already.
For the first question, Andre, if you’d like to come on camera, I’ll send this one to you: Is book and claim only available to a fleet through an RFP and award, or can a fleet that has battery electric vehicles sell the EAC directly to a shipper?
ANDRE DE FONTAINE:
Yep. Okay, that’s a really good question — thank you to whoever asked it. There are a couple of ways of answering it, but I’ll start by stating our objectives at GMA: we are trying to get more battery electric trucks on the road, and we think book and claim is a very effective mechanism for doing so.
Our goal is not to corner the market for EACs or to run the only pathway for purchasing them. Already today, fleet owners can sell attributes directly to shippers, and we’re seeing some services and companies do so. What we’re really trying to do is create a market for these attributes. So no, it doesn’t need to go through GMA.
Having said all that, what we’ve experienced in other sectors is that in the early stages of these markets, there is a lot of benefit to working through an NGO platform to buy and sell certificates. We certainly hear that a lot from the buyers we work with, who are venturing into a new market that poses some risk and presents a lot of complexity. They like working through a managed process with experts who have done this kind of work in other sectors.
But as the market matures, we fully expect to see other purchasing pathways begin to flourish. This is something we saw with the Sustainable Aviation Buyers Alliance. In the early stages of the SAF certificate market, a lot of traffic went through SABA. Today, the most significant transactions are actually occurring outside of SABA, but they are leveraging a lot of the tools and market infrastructure we built, whether it’s the digital registry or the sustainability framework that sets the criteria for high-integrity SAF certificates. We could definitely see a similar trajectory in trucking.
I hope that answers the question. The bottom line is that there are, and will be, multiple pathways for engaging the market. We think we play a pretty important role in the early stages, but as the market grows, we would expect to see multiple different pathways for trading attributes.
STACEY MCCLUSKEY:
Great, thank you, Andre. Our next question relates to slide 16, so let’s go back to that slide so we can reference it. How is Carrier A managing and treating its Scope 2 emissions? Clayton, would you like to take that one?
CLAYTON GERBER:
Yeah, sure thing. Let me just make sure I’m on the right slide. So Carrier A here is the one actually operating the electric trucking service and the electric truck itself.
In line with how corporate GHG accounting works, they are also able to count those emissions toward their own targets and their own emissions report. The Scope 2 emissions in this case will be gathered from the charging infrastructure or the telematics, following all the relevant greenhouse gas accounting rules, and they can report that as their Scope 2. They’re operating these trucks, so it’s part of their reporting inventory.
That’s allowable double counting, so to speak. As Jakob mentioned earlier in the presentation, emissions across the value chain actually overlap with one another. A carrier’s Scope 1 or Scope 2 is the same as its shipper’s Scope 3. That’s the intention of the different GHG scopes: to provide an incentive for shippers to decarbonize and to make them accountable for emissions that aren’t within their direct operational control.
So if I’m understanding the question correctly, the Scope 2 emissions would simply be part of Carrier A’s report. They would be able to report and claim them and make external communications about their emissions. If they’re a large carrier with both diesel and EV services, they would similarly be able to report lower emissions in their corporate reporting because of the shift from Scope 1 to Scope 2, or just the Scope 2 itself.
It’s important to note — and I think there’s another question we’ll get to on this — that if the carrier is selling a certificate from that activity, the emissions profile of that electric service can’t then be used by the physical customer receiving the service. The physical customer has to use a default or residual factor that essentially does not reflect the electric nature of the truck.
So I think I’ve answered a couple of different questions — I hope one of them was the intended one.
STACEY MCCLUSKEY:
Perfect, thank you. Our next question: If book and claim certificates are coming from a carrier — for example, J.B. Hunt — but I don’t use J.B. Hunt for any transportation, can I still buy J.B. Hunt credits through book and claim and apply them to meet my carbon target goals? Jakob, I’ll send that one to you.
JAKOB SANCHEZ:
Yeah, and I think we can stay on this slide, too.
So, in short, yes. It does not require the carrier you use to be the same carrier you buy a certificate from.
The caveat I would include is that when using market-based instruments like these book and claim certificates, best practice and the rules say we wouldn’t want to buy certificates from Class 8 heavy-duty trucks and apply them to, say, your passenger commuting footprint. We call this constraining by the transport operation chain, or TOC. So we would want to see TOC matching and bounding. We would also not want to purchase more certificates than what is actually reflected in our inventory.
As for who those certificates come from, this is exactly the solution book and claim offers: they can come from anyone, regardless of geography. As long as you’re motivated and willing to pay for it, you will receive those environmental attributes. But yes, there are a couple of constraints and rules around how those certificates are actually applied, and that’s a topic we’ll want to dive into a lot more deeply in a future webinar.
CLAYTON GERBER:
One thing I might add here, Jakob — you covered everything, but one thing that came to mind is that over time, as these markets mature, there can be an evolution toward additional matching criteria. For those familiar with the renewable energy market, for example, we’re seeing a trend, after 20 or 30 years of operation, toward requiring more connectivity.
We’re very early in this market. At this point, we don’t see further constraints — based on very specific routes or lanes — as needed, or as really manageable or feasible. Over time, we may get to a place where we as an organization promote best practices that get stricter and stricter. But we’re early enough in the maturity of both book and claim in this sector and electric trucking in general that we don’t think further matching should be required or even recommended — especially as it relates to whether you need to do business with a specific carrier.
STACEY MCCLUSKEY:
This next question relates to ZET SCALE: Under ZET SCALE, are the shippers not expecting EACs to be bundled with their physical demand? Clayton, I’ll send that one to you as well.
CLAYTON GERBER:
Awesome. Yeah, thank you for the question. It’s a great one, and it’s one we want to make sure is crystal clear to everybody engaging on the book and claim side.
The expectation is that those involved in ZET SCALE are interested in the environmental attributes. They are motivated by the greenness, so to speak — the emissions impact of the electric deployment.
So when we think about combining physical demand and book and claim demand, the actual activity underlying the book and claim certificate needs to come from shippers who are not interested in the environmental attribute, because they have to forgo the rights to it in order for it to be claimed by a different shipper through the certificate.
Here’s how that could work. As a carrier, you might have a contract or book of business with a motivated shipper, potentially part of ZET SCALE. Let’s say that, in a certain region, it covers 70% of the utilization you need from that truck to reach your targets. For the remaining 30%, you might not otherwise be able to win business from other shippers in the market who aren’t motivated by electrification — who are just cost-conscious and want their goods moved with high-quality operations and terms, but aren’t necessarily looking for a lower-emissions service.
Those are the opportunities where book and claim can help reduce the revenue you need to charge. You don’t necessarily need to charge a premium or higher cost to the physical customers in that region who don’t care about the greenness of the trucks. You can use the revenue from the book and claim certificates to be more competitive in the market and therefore win other business.
We’ve seen several of the carriers engaging in this market working a lot with 3PLs, for example, to identify and source routes — working both on contracted business with shippers and on more day-to-day spot market business.
So, long story short: the ZET SCALE shippers are motivated by the attributes, so the certificates need to come from business with shippers who are not interested in the attributes. And it’s the certificate revenue that provides the flexibility to go out and find those shippers.
STACEY MCCLUSKEY:
Jakob, I’ll send this next question to you. If I’m selling the environmental attributes, can I still market myself as a zero-emission carrier to physical customers?
Jakob SANCHEZ:
Yeah, this is a good and tricky one.
Yes, but — big but — if you’re selling the environmental attributes of your trucking service, you have to be very clear when contracting with your physical supply chain that anybody receiving your service on a route for which you’ve already sold the attributes cannot also claim them. This is where we start to get into double-claiming and double-counting territory, which we will definitely cover in more depth.
But yes, as an all-electric carrier, you can say that you are deploying electric trucks and having a positive impact on the decarbonization of the freight sector. You can point to your positive benefits in the marketplace broadly. But it’s important to be very clear — and best practice is to be contractually clear — that your physical customers cannot claim the greenness of your electric trucks if you’ve already sold that off.
This is where it becomes really important to be very transparent about your use of market instruments, so that all the players in the ecosystem can act responsibly and accurately.
STACEY MCCLUSKEY:
Thank you. Clayton: How do I know there will be buyers for these attributes in the future?
CLAYTON GERBER:
Yeah. To be honest, we feel this is kind of our role in this market. As the demand aggregation function, we bring together the companies that are motivated and interested in this market, and we try to take out the uncertainty — especially in each discrete procurement process — by providing a long-term contract. In the first procurement, that was a four-year contract with options on the back end to extend. That takes some of the ambiguity out and gives carriers engaging in the procurement process assurance that they will, in fact, receive that revenue for the duration of the contract.
More generally, we see a lot of positive momentum around the adoption of these kinds of instruments beyond our procurement process. With SBTi — the target-setting initiative Jakob mentioned, which is one of the factors driving many companies to engage — we’ve seen a lot of positive movement toward accepting these kinds of mechanisms. Previously, there was ambiguity about whether they would count toward targets. Now it’s pretty clear that they can count toward targets for companies that want to reach those goals.
As a result of SBTi and the GHG Protocol, we’ve seen increased interest from corporate shippers across trucking, as well as other transport modes and other sectors generally.
So overall, we take our demand and try to make it bankable and set in hard contracts, so you know it’s assured and you know it’s there. And through the repetition of these procurement cycles, we hope that creates assurance in overall demand.
STACEY MCCLUSKEY:
We have time for one more question, so I’m going to go to Andre. Why should I buy EVs now instead of waiting for truck prices to fall?
ANDRE DE FONTAINE:
Well, I’ll answer this from an environmental perspective. You sometimes hear the expression, when it comes to climate change, that winning slowly is the same as losing. That’s definitely something that motivates our urgency at GMA.
I think we went over some pretty clear benefits of purchasing and deploying these trucks. In many cases, you can start to see TCO parity. But even absent that, the local air pollution benefits, the insulation from some of the risks of the fossil fuel market, and the fact that they’re a better ride for drivers — the benefits are clear and present now. We don’t know exactly what will happen with truck prices in the future, but I think there are strong enough reasons to act now that it makes sense to get into this market and start taking advantage of those benefits.
STACEY MCCLUSKEY:
Well, that’s all the time we have. Thank you, everyone, for attending the first webinar in our carrier education series. As mentioned at the beginning, our next webinar will be on November 10th at 1:00 PM Eastern / 10:00 AM Pacific. We hope to see you then.
Also, keep an eye out for our request for information, or RFI, which will launch later this week or early next week. You’ll receive an email about that as well.
Thank you all very much for attending, and we look forward to seeing you at the next one.
CLAYTON GERBER:
Thanks, everyone.
ANDRE DE FONTAINE:
Thank you.
Related News & Resources
10.01.26
GMA Trucking | Building Momentum for Decarbonized Road Freight
In late 2024, GMA Trucking launched a first-of-its-kind Request for Proposal (RFP) for zero-emission trucking attributes, seeking to deploy Class 8 battery-electric trucks (BETs) across the contiguous United States and connect carriers with first mover corporate customers committed to decarbonizing road freight.
At the end of 2025, the impact of the RFP became real, with contracts signed that will lead to more than 60 new trucks on the road and chargers in the ground beginning in 2027. The procurement also led to new partnerships and opportunities that will lead to larger deployments and greater impact.
The momentum is continuing to grow. With a new buyer joining the pilot, the most supportive standards landscape book and claim models have seen, and a registry provider now in place, GMA Trucking is scaling up for its next procurement and looking to increase its impact.
Revisiting GMA Trucking Pilot Procurement Highlights
GMA Trucking, a program of the Center for Green Market Activation (GMA), is a buyers alliance designed to accelerate the deployment of zero-emission heavy-duty trucking by addressing market barriers, including high vehicle costs, limited charging infrastructure, fragmented freight demand, and complex Scope 3 supply chains. This is done through a book and claim system that decouples the Environmental Attribute (EA) of the low-emission service from its physical delivery. In effect, this allows corporate buyers interested in decarbonized on-road shipping to purchase and claim verified Zero-Emission Trucking certificates (ZETc) against their climate targets while carriers operate zero-emission trucks wherever they can achieve the greatest operational and financial efficiency.
In December 2024, GMA launched a competitive RFP to trucking carriers seeking to deploy Class 8 battery-electric trucks powered by renewable electricity (or qualifying hydrogen fuel-cell trucks) across the contiguous United States. Nevoya, an AI-native, all-electric class 8 carrier operating in California, Texas, and Arizona, won that first, “pilot” procurement and contracts are now executed, with the first certificates slated to be generated and delivered in early 2027. Importantly, the investment buyers have made to deploy new battery-electric vehicles and infrastructure sends a strong signal to carriers that zero-emission freight is real, ready, and in demand.
Increasing Impact: A New Buyer Joins the Pilot Procurement
Recognizing the opportunity to drive more impact, Google joined the initial cohort of corporate buyers in late summer of 2026.
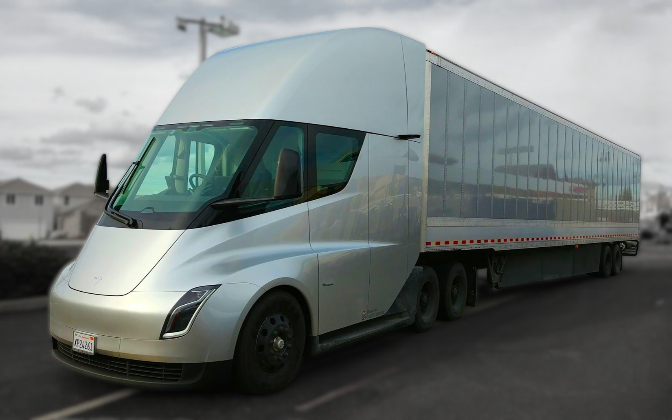
Google’s entrance as a member and buyer in the pilot significantly increases the total number of trucks deployed by the original group, unlocking further economies of scale and deepening the benefits of demand aggregation. More than 20 new battery-electric trucks will be added to the project because of the increased investment, bringing the total deployment to 63 Tesla Semis charged on Greenlane’s Texas network, operating between Houston and Dallas beginning early 2027. These trucks are expected to travel up to 11 million miles annually, reducing an estimated 92,000 metric tonnes of CO2e as compared to diesel trucks over the four-year contract.
Google’s decision to join the pilot speaks to the confidence buyers are placing in book and claim and the value of joining a project to increase scale and impact.
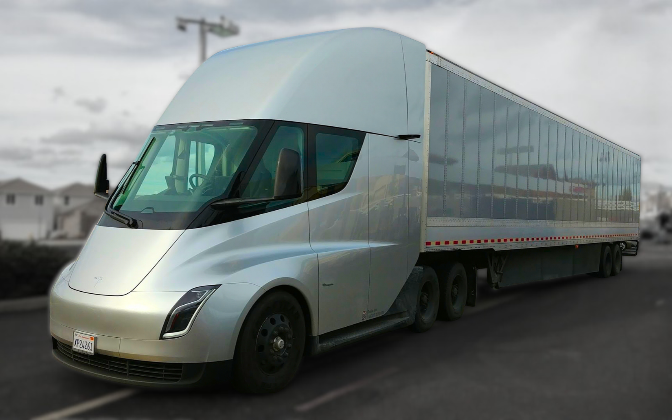
A Tesla Semi, the type of truck that will be deployed in the project
An Evolving Standards Landscape Supportive of Book and Claim
Corporate confidence in the book and claim model has been further strengthened by a series of updates unveiled by critical standard setters that recognize and legitimize environmental attribute certificates (EACs) as a valid tool for companies to reduce their value chain emissions. These standards signal support for book and claim while also providing tactical guidance that can help companies navigate these emerging markets.
Companies can now turn theory into action with the backing of accepted guidance.
AIM Platform Standard and Guidance
The AIM Platform Standard and Guidance, published in April 2026 by the Advanced and Indirect Mitigation (AIM) Platform, offers companies a credible way to account for and report on value chain interventions, such as ZETc procured through GMA Trucking.
Corporate Net-Zero Standard V2
In June 2026, the Science Based Targets initiative (SBTi) released version two of their Corporate Net-Zero Standard (CNZS V2). Updated from V1, the new Standard explicitly recognizes market-based instruments, including EACs from book and claim systems, as legitimate tools companies can use to implement their climate targets.
GHG Protocol Corporate Standard
The Greenhouse Gas (GHG) Protocol is also in the process of making major revisions. In its March 2026 Action and Markets Instruments (AMI) Phase 1 Progress Update White Paper, the GHG Protocol proposed a multi-statement reporting structure for discussion. The proposal, much like the one outlined in the AIM Standard, would allow companies to report a market-based inventory and impact statement alongside their physical emissions inventory, giving buyers of instruments, such as ZETc, a clear and transparent way to report their efforts toward value chain decarbonization.
The update to this Standard is being eagerly anticipated. While SBTi has given the green light to counting EACs toward corporate climate goals in CNZS V2, it has deferred underlying questions about how to account for these instruments in GHG inventories to the GHG Protocol. Important work still needs to be done in this area.
In July 2026, GHG Protocol announced a consolidation of its Corporate Standard, Scope 2, Scope 3, AMI, and ISO’s 14064-1 workstreams into a single, harmonized standard, with an integrated public consultation planned for Q2 2027. While the final standard will likely not be finalized until late 2028, the direction of travel is clear and companies should feel confident they will have an avenue to report EACs, like ZETc, under the GHG Protocol and ISO.
SFC Market Based Measures Framework
The Smart Freight Centre’s (SFC) Market Based Measures (MBM) Framework is also undergoing a revision process ahead of V2 release. This transport-specific document is expected to help fill in some gaps in both the SBTi and AIM Standard for how EACs can be claimed and accounted for, covering such issues as functional unit for issuance and accounting, additionality, issuance process flow and others across transportation modes. A version for public consultation is expected late 2026, with the final Framework set to be published Q1 2027.
While the asynchronous and overlapping nature of the book and claim standards landscape can appear daunting and confusing, behind the scenes many of the key entities and stakeholders working on these issues are in close collaboration and share the goal of greater consistency and alignment. Convergence is appearing, with even greater clarity on key rules and protocols expected in the months ahead.
Establishing Essential Market Infrastructure
Registries are an essential component to a book and claim system, preventing double counting and issuance and validating the claims of the certificate purchaser. They operationalize the standards companies follow when they book and claim EACs by providing the transparency, verification, and documentation needed to ensure the attributes are appropriately created, transferred and retired. GMA Trucking will be working with 123Carbon, a digital registry for environmental attributes across transport sectors, to house the certificates issued through the pilot procurement. 123Carbon has developed a module specific to battery-electric trucks that can track all relevant data to enable transparency and accurate reporting to the participating buyers. GMA is working closely with 123Carbon to ensure that all required information is captured and tracked in alignment with the procurement’s design.
Looking Ahead: Ramping Up for Future GMA Trucking Procurements
Building on the pilot’s success, and with critical market infrastructure coming into place, GMA Trucking is scaling up for the next procurement.
The second procurement is set to launch in early 2027. To maximize impact and drive catalytic investment, GMA Trucking is looking to use its book and claim model to complement other initiatives in the market, including those seeking to aggregate physical demand.
Our expectation is that coordinating physical with book and claim demand aggregation will lead to better economics, scaling the sector faster than either one on their own. The long-term revenue certainty offered by book and claim provides carriers with stronger assurances and financing, leading to more competitive freight rates against incumbent diesel trucks. This, in turn, drives more utilization, as shippers gravitate towards carriers offering competitive rates. As zero-emission trucks are utilized more, ZEV carriers save on operating expenses compared to diesel trucks, maximizing savings and covering any upfront capital or resources used in the switch to electric. The result is a positive, reinforcing cycle, where the ZETc purchaser, carrier, and physical shipper can all enjoy lower prices, revenue assurances, and meaningful emissions reductions in the heavy-duty trucking sector.
Book and claim can help support the positive feedback loop that drives more deployment, lowering costs for all
Members of GMA Trucking have spent the past several months shaping the structure of the second procurement directly, weighing in on requirements, contract terms, corridor priorities, and how book and claim can complement other efforts. Companies who join GMA Trucking now still have time to help shape procurement design before the RFP launches, a level of influence that won’t be available once the procurement is underway.
Certificates from this next procurement are expected to be generated and delivered ahead of and into 2030, meaning companies with decade-end targets have a real, near-term decarbonization lever, backed by a standards landscape that’s more supportive of this approach than it has ever been.
Next Steps for Interested Companies
The time to take action towards decarbonizing value chains is now.
GMA Trucking’s pilot proved the model works; real trucks, real corridors, real emissions reductions, and a buyer base that’s already growing. The second procurement is your chance to help shape what comes next.
Reach out to trucking@gmacenter.org today to start the conversation.
Related News & Resources
05.08.26
One Pager | Applying a book and claim model to drive decarbonization of heavy-duty trucking
This one page pamphlet explains how GMA Trucking applies a book and claim system to heavy-duty trucking and how emission benefits are calculated.
Related News & Resources
02.25.26
GMA Insights | Key Takeaways from GMA Trucking’s New White Paper
For the latest edition of GMA Insights, we’re taking a look at a new white paper released just this week, “Accelerating Momentum for Zero-Emission Trucking: Lessons Learned from GMA Trucking’s Pilot Procurement.” Assembled by the GMA Trucking program team, it offers a detailed examination of the market challenges GMA Trucking seeks to address, the critical role of demand aggregation and book and claim in addressing those challenges, and key findings from GMA Trucking’s recently concluded pilot procurement that will deploy 40 new battery electric trucks in the state of Texas.
The white paper, available for download here, includes an exploration of lessons learned that can be applied to future efforts, describing the pilot procurement as “an invaluable opportunity to explore the real-world dynamics of the zero-emission trucking market” and “a test case to identify friction points, gather actionable data, and understand the values, priorities, and constraints of different stakeholders.” A summary of insights follows.
Lessons Learned on the Benefits of Book and Claim and Demand Aggregation for the Zero Emission Trucking Market
- 1. Book and claim incentivizes and enables increased truck utilization above typical, current battery electric vehicle (BEV) usage, significantly reducing costs per mile.
- 2. Increased demand, aided by the flexibility of book and claim, can enable charger maximization and optimization, spreading CAPEX across more trucks and decreasing service costs.
- 3. Book and claim allows longer contract periods and the ability to spread costs over an extended time horizon with increased assurance of charger and truck utilization, leading to a reduction in overall project costs and increased bankability.
- 4. Innovative contract structures with tiered pricing of attributes reduces risk exposure, ensures high-integrity outcomes, and aligns incentives across parties.
- 5. A single entity facilitating alignment on key terms such as the criteria for high-integrity zero emission trucking certificates (ZETC), minimizes administrative burden when multiple parties are signing contracts.
Additional resources:
- Press release: First Ever GMA Trucking Procurement Brings Together Leading Companies to Enable Largest Known Deployment of Class 8 Battery Electric Trucks in Texas
- Webinar and Q&A: Webinar Q&A | GMA Trucking’s Pilot Procurement: Lessons Learned and the Road Ahead
- Frequently Asked Questions, including definitions of often-used terms like book and claim and demand aggregation
Interested in getting involved with GMA Trucking? Email trucking@gmacenter.org to get started.
Related News & Resources
02.25.26
White Paper | Accelerating Momentum for Zero-Emission Trucking
This white paper, published in February 2026, outlines key insights from GMA Trucking’s pilot procurement, designed to accelerate the deployment of zero-emission heavy-duty trucks through aggregated corporate demand and a book and claim system, and shows how these methods can overcome financial, operational, and contractual barriers that have slowed adoption of decarbonized freight technologies. The paper highlights lessons on cost reduction, risk-sharing, infrastructure utilization, and long-term contracting that can inform future procurements and scale zero-emission trucking solutions.
Related News & Resources
02.05.26
Webinar Q&A | GMA Trucking’s Pilot Procurement: Lessons Learned and the Road Ahead
In January 2026, GMA Trucking announced the results of its pilot procurement that will enable the largest known deployment of Class 8 zero-emission trucks in Texas, and which showed the effectiveness of a market-based approach to accelerate deep decarbonization within the heavy-duty trucking industry. Shortly following the announcement, GMA hosted a webinar featuring GMA Trucking team members, the winning carrier Nevoya, and representatives of two corporate buyers discussing the procurement, lessons learned, and the road ahead. A recording and transcript can be found here. The compiled Q&A from that webinar is shared below. This includes questions that were answered live during the webinar, as well as those left unaddressed during the session because of time constraints. Please reach out to trucking@gmacenter.org with any further questions.
| Question | GMA Trucking Answer |
| How are the environmental attribute certificates (EACs) certified/verified? | The ZETc will be verified by an ISO 17029 accredited verifier for the application of ISO 14065, and in alignment with the requirements of ISO 14083 to calculate the emissions intensity of the transport activity (gCO2e/tonne-km). |
| Will the environmental attributes be sold and transferred via a registry? | Yes. Third-party registries are a critical part of the EAC market to ensure transparency and credibility. GMA Trucking is currently finalizing the registry provider but expects to have a functioning registry in time for the first generation of attributes to ensure accurate tracking and transparency. |
| Approximately how many years does it take for the lower operating costs to reach breakeven with the purchase cost of a battery electric vehicle? | There is no uniform answer, as both capital and operating costs will vary significantly across deployment opportunities. It depends on many factors, such as, but not limited to: vehicle mileage, diesel price, electricity price, demand charges, charging ownership model, charging infrastructure costs, and others. This leads to a wide range of payback periods, from only a few years[1][2], to many years, or possibly never. |
| How do zero-emission truck sales compare to overall truck sales? | While global sales of zero-emission medium- and heavy-duty trucks are slowly increasing (on pace for upwards of 4% of all new sales in 2025), that increase is driven almost entirely by China, where sales approach 15%[3]. In contrast, the U.S. market has stalled. Bloomberg NEF and Smart Freight Centre’s Accelerating the Transition report notes that zero-emission truck sales peaked at under 0.5% in Q2 2024 and dropped below 0.1% in the first half of 2025, with fewer than 200 zero-emission medium- and heavy-duty trucks sold nationwide[4]. This is in contrast to the over 200,000 diesel class 8 trucks sold in the same year. |
| Are 45V tax credits for clean hydrogen production still up under the new administration? | Yes, though the deadline for projects to begin construction has shortened. Projects must now start construction prior to January 1, 2028. |
| What is the energy source powering the winning carriers’ electric vehicles, and is GMA Trucking basing its analysis on Well-to-Wheel calculation? | Yes – ZETc are based on well-to-wheel (WTW) emissions intensity. As part of the RFP, GMA Trucking specified that the charging infrastructure used must be backed by renewable electricity. This could be accomplished either by using behind the meter on-site renewables or by purchasing a renewable energy product (e.g., Green-e eligible REC) equal to the volume of electricity utilized to charge the vehicles.
The energy used for trucking services will align with GLEC Framework and ISO 14083, which provides the methodology to measure the WTW emissions intensity per transport activity (tonne-km). This includes an approach to account for losses in the charging infrastructure while considering the data sources available. Per the standard, both location-based (using grid intensity) and market-based (using any contractual electricity certificates) emissions intensities will be calculated. |
| At what point in the process are vehicles purchased by the winning carrier? | The pilot RFP was open to bids for existing and/or net-new vehicles, though there was a preference for net-new.
For existing vehicles, GMA Trucking only considered vehicles that were already deployed but underutilized, or deployed but operating at a loss. |
| When will the trucks be deployed? | GMA Trucking expects the trucks generating the EACs to be deployed and in operation by the end of 2026 or early 2027. |
| Was the winning carrier able to fully satisfy the demands of the GMA Trucking members? | Yes, Nevoya is able to satisfy the final demand of GMA Trucking members. |
| What incentivizes shippers to buy EACs? | Shippers purchase EACs to meet their climate goals when decarbonized trucking services are not available on the routes used to physically move their goods. In these instances, shippers use EACs as a tool to complement their ongoing efforts to push their direct logistics providers to decarbonize their operations. |
| Is GMA Trucking’s model structured so that the EACs are only sold with the Scope 3 attribute, or also Scope 1? | The GMA Trucking program is set up for corporates to buy scope 3 EACs only – the carrier driving the zero-emission trucks claims any impact on scope 1 or 2 emissions. |
| Has GMA Trucking considered sharing lessons learned or releasing recommendations for these types of agreements? | Lessons learned from GMA Trucking’s pilot procurement will be shared in an upcoming White Paper. We are excited to connect with the market to share what we can about EAC offtake agreements. |
| How do you see GMA Trucking’s program scaling? | A key focus for GMA is to grow and scale programs past the pilot stages. The results from the GMA Trucking pilot will drive momentum and interest to scale up future efforts for larger impacts. It will also provide us, and the members, with the information and supporting infrastructure to transact more efficiently, including base contracting language and registry issuances. The standards landscape is also positioning to bolster demand for the program, as SBTi, GHGP, and AIM plan to release updates on the inclusion of market-based mechanisms like ZETc in coming months.
GMA Trucking is currently considering how to structure its next RFP and is considering how it may pair book and claim with physical procurement. |
| Will a recording of the webinar be shared publicly? | Yes. The recording, slides, and a transcript can be found here. |
[1] https://theicct.org/cost-electric-semi-feb22/
[2] https://www.terawattinfrastructure.com/blog/how-to-better-predict-your-ev-fleets-total-cost-of-ownership
[3] https://assets.bbhub.io/professional/sites/24/Zero-Emission-Commercial-Vehicles-Factbook-2025.pdf
Related News & Resources
Heavy Duty Trucking

Heavy-duty trucks constitute a significant and growing share of greenhouse gas (GHG) emissions. Globally, heavy-duty vehicles account for more than 1.2Gt of CO2e emissions, while only approximately 4% of new medium- and heavy-duty vehicles sold are battery electric vehicles (BEV) or fuel cell electric vehicles (FCEV). By bringing together trucking customers with carriers, truck manufacturers, and infrastructure providers, GMA Trucking channels funds for low-carbon trucks in regions where deployment is otherwise lagging.
GMA runs GMA Trucking, a buyers alliance that leverages corporate demand to decarbonize heavy-duty trucking, with a focus on procurement of zero-emissions trucking service attributes. With member companies from tech, e-commerce, consumer packaged goods, and other sectors, GMA Trucking has a proven record of directing demand through multi-year contractual agreements that enable carriers to purchase and deploy zero-emission1 heavy-duty vehicles. This form of offtake is made possible by the book and claim system developed by the Smart Freight Centre’s Market Based Measures Framework and GMA’s expansion on best practices for zero-emission certificates issuance and reporting. GMA Trucking is proud to have the Smart Freight Centre as a strategic partner for the program to help build on MBM application and battery electric truck expertise.
1 “Zero-emission” trucks refers to tailpipe emissions only, not inclusive of upstream manufacturing emissions.

Heavy duty vehicles contribute more than 1.2 Gt of CO2e globally
Trucks emit 1/3 of on-road greenhouse gases

Only ~4% of new class 8 trucks sold are battery electric or fuel cell electric
Member Benefits
Clear guidance and expert support on the identification of high integrity decarbonization opportunities
Access to joint procurement opportunities with potentially lower prices via group RFPs
Educational support on how purchasing environmental attributes can support credible emissions reductions and how to account for them in your inventory.
Program Members




Strategic Partner

Testimonials

Related News + Resources
01.20.26
Webinar | GMA Trucking’s Pilot Procurement: Lessons Learned and the Road Ahead
In this webinar recorded on January 15, 2026, GMA was joined by representatives of Nevoya, Etsy, and Amazon to discuss the groundbreaking GMA Trucking pilot procurement that will enable the largest known deployment of Class 8 zero emission trucks and associated charging infrastructure in Texas.
Learn more in GMA’s January 15 press release.
See below for a full transcript of the webinar. Presentation slides can be accessed here. Additionally, questions asked during the webinar were compiled and answered here.
ANDRE DE FONTAINE:
Welcome everyone and thank you all for joining us today for this webinar that we’re hosting to do a bit of an overview and lessons learned from our recently closed procurement for the environmental attributes of low-carbon trucking services. So that’s a bit of a mouthful, but we are going to spend some time today really unpacking that and talking about its significance. And so if you could go to the next slide, please.
My name is Andre de Fontaine. I’m a managing director at the Center for Green Market Activation, and I’m really thrilled to have a great set of speakers that are going to help us really communicate what we just did. That includes on the GMA side, Clayton Gerber, the program manager for GMA Trucking, which really led a lot of this work, and then also Stacey McCluskey, who is a program associate at GMA and provided a lot of great support.
So those are the speakers from the GMA side, but we had a much bigger team that was supporting this initiative to make sure that it could be successful, including Sam Pearl Schwartz, a manager from GMA, James Line, who was formerly an intern, and then also Allison Green, who led all the communications efforts, and of course, Kim Carnahan, our president and CEO.
We are very fortunate to have with us today a group of speakers, participants in this deal, who are going to talk about some insights and perspectives, and this includes JV, who is a co-founder and chief commercial officer from Nevoya. Nevoya is the all-electric carrier that was selected through a competitive process to provide the services that our members are purchasing. You’ll hear more about that shortly.
Then we also have a couple of the shippers or GMA trucking members that really, this wouldn’t have been possible without their leadership throughout this initiative. That includes Eleanor Bastian, senior manager from Amazon, and Sam Brundrett, who is the environmental sustainability lead from Etsy. If you can go to the next slide, I’ll talk a little bit about what we are hoping to accomplish today.
So what we’re going to do is an overview of this procurement process, but more importantly, we want to focus in on the lessons learned. This initiative combined book and claim with demand aggregation. It was complicated. We’re not aware of anyone else having done this before. And so with that, there was a huge amount that we learned that we want to capture and convey. And the reason for that is that we think that these mechanisms have a lot of potential to unlock more investment in low carbon, heavy duty freight. And so we want to do more of it.
So with that, it’s important that we capture the lessons learned and take it forward to new and hopefully bigger initiatives into 2026 and beyond. So I will start what I’m doing right now, which is just a bit of the welcome. And then I will pass it over to Stacey that’ll do a deeper dive on the overview and results from the RFP process. We’ll then ask JV from Nevoya to provide some insights from the carrier perspective. Then Clayton will walk us through some of the lessons learned through the initiative, and then we’ll pass it over to both Etsy and Amazon who can speak from the shipper perspective. We’ll do a bit of a look ahead to future initiatives.
Then if we stay on time, and I hope we will, we should have about 10 minutes or so for Q&A. For those of you that are participating on the webinar, please use the Q&A button to type in your questions, and then at the end of the webinar, we’ll see how many we can get through. It depends on how much time we’ve got.
One other logistical item, we are, you’ve probably heard the voice at the outset, we are recording this webinar. So be advised that it is being recorded.
Now if you go to the next slide, I know that we’re eager to jump into the meat of the content, the specific lessons learned. But before doing so, I wanted to provide just a really quick background on the Center for Green Market Activation, or GMA, as we’re more commonly referred to. So we’re a relatively new nonprofit. We were launched in July of 2024. We’re focused on decarbonizing what are commonly referred to as the hard to abate sectors. So this is your heavy industry and your heavy transport inclusive of heavy duty trucking. The premise behind much of our work is that voluntary corporate demand can be a really important lever to drive change in these industries.
But there are currently a lot of pretty significant barriers that stand in the way that prevent customers and customers that are motivated to purchase low carbon goods and services to meet their ambitious climate goals from actually purchasing those goods and services. So what we’ve been trying to do is to develop mechanisms that can more efficiently connect the producers of those goods with the buyers.
We’ve focused a lot on book and claim. We’ll talk more about this through the course of the webinar, especially its application to trucking. But essentially within book and claim, what you’re doing is you’re separating the environmental attribute from the physical product. When you do so, it creates more flexibility in the system, opens up more demand sources and expands the investment playing field.
Alongside that, what we do is we aggregate demand through these buyers’ alliances. Through that, rather than limiting ourselves to bilateral purchasing, we’re pooling demand across several buyers to send a larger demand signal. That ideally creates the confidence for the producers to scale up more rapidly because they know that there is a group of customers that are out there that are willing to pay the premium and make the investments needed to purchase these low-carbon goods and services. If you advance to the next slide, I’ll talk a little bit more about where we’re active currently.
So we do all of this work in partnership with other NGOs. In the aviation space, SABA is our most mature program. It’s been around the longest, and we do that in partnership with RMI and EDF. In maritime, we support the Aspen Institute, which leads the Zero Emission Maritime Buyers Alliance, and then Trucking, which is the focus of today, we do with our partners at the Smart Freight Center. We recently launched SCoBA, which is the Sustainable Concrete Buyers Alliance, focused on cement and concrete, and that’s also in partnership with RMI. Then as far as the developing initiatives, chemicals is actually pretty far along, and this is another initiative that we do alongside RMI.
So if you go to the next slide, I will spend not much time here because this is really going to be what we expand upon over the course of the remaining time that we have together. The major components or the scope of this effort includes demand aggregation. This is the process of bringing motivated shippers and a few freight forwarders together, understanding how much and what they want to purchase. We were able to leverage the SFC’s market-based measures framework for the book and claim system design, then we identified a high-quality project and route through a competitive RFP processes. This is how we landed on the Nevoya route that we’ll talk about more.
Then finally, contract facilitation. This is a really important part of the process, because we really think it’s important to go from commitment all the way through contracting. The contract is what ultimately unlocks the investment, and it was complex. We’ll talk a little bit more about this as we go through the webinar, but there was a lot that we learned through the contracting process that we are excited to share today.
So with that, I will stop talking and pass it over to Stacey, who’s going to do a little bit more of a detailed overview of the program and the process.
STACEY MCCLUSKEY:
Thanks, Andre. As Andre mentioned, I’m going to be walking through our approach to addressing the road freight challenge. Now, much of this has been covered in previous GMA Trucking webinars, so we’re going to move through it kind of quickly. But if you have any questions, you can find additional resources on our website, or we’ll have time at the end for Q&A.
Heavy-duty trucks are a massive source of global emissions, accounting for roughly 3% of global energy-related emissions. To stay on a net zero trajectory for 2050, we need zero emission trucks to make up 35% of sales by 2035. While some markets like China are moving in that direction, the U.S. market has essentially collapsed. Sales peaked at less than half a percent last year and have since dropped to nearly nothing, with fewer than 200 electric trucks sold in the first half of 2025. That is an 80% decline compared to the same period in 2024.
Policy rollbacks haven’t helped, but this isn’t just about regulation. Even at its best, the U.S. barely sold 700 zero-emission trucks in one quarter. Next slide, please.
The challenges to deploying zero-emission vehicles are numerous, but four really stand out. The vehicles and charging infrastructure are costly, significantly more so than traditional diesel trucks. Corporate customers interested in decarbonizing often find their trucking emissions are buried deep in their value chain, making them difficult to identify and address. Further complicating that issue is the use of third-party logistics providers, which add a degree of separation from the carrier. And even when shippers connect directly with carriers, short-term logistics contracts conflict with the long, useful life of the vehicles that the carriers have purchased.
So without confidence in long-term demand, these carriers just can’t justify the premium for zero-emission trucks. These challenges won’t resolve quickly on their own, so we need new tools. GMA Trucking’s book and claim system is just one lever that can make zero-emission trucks deploy in near-term.
Book and claim, as Andre mentioned, decouples the physical shipping service from the environmental attribute, and that’s what we at GMA Trucking call zero emission trucking certificates, or ZETcs. Though newer in the on-road transport sector, many of you are likely familiar with this concept in other sectors, like RECs for electricity and sustainable aviation fuel certificates for aviation.
Unlike those, though, where, for instance, in electricity, the functional unit of a wreck is the quantity of energy, meaning one megawatt hour of renewable electricity, the functional unit in the trucking sector is the quantity of trucking service provided, meaning moving one ton of goods, one kilometer on a zero-emission truck.
Let’s kind of put this into an example. Let’s say Shipper 1 wants to transport their goods on a zero-emission vehicle, but is unable to find a carrier or a route that supports that. As such, Shipper 1 is going to continue to move their goods through Carrier A, which in this example is a traditional diesel trucking service. Because Shipper 1 is able to move their goods on a zero emission vehicle, they decide to buy a ZETc issued by another carrier, in this case Carrier B. Because Carrier B is selling ZETcs through a book and claim model, they’re able to deploy the zero-emission vehicles in geographies and on routes that are most economical for them, even if the physical shippers on those routes don’t want to pay the premium associated with the zero-emission trucking service.
As such, Shipper 1 contracts with Carrier B to procure the environmental attributes associated with their service. Carrier B is still transporting another shipper’s goods at diesel prices, while Shipper 1 pays the premium associated with operating the zero-emission vehicle in exchange for the ZETc. By procuring the ZETc, Shipper 1 is allowed to claim the resulting emission benefit from Carrier B’s usage of the zero-emission truck. Meanwhile, Shipper 2, whose goods are still being transported by Carrier B, cannot account for or claim the zero-emission reduction.
I also want to note that this example shows two different carriers on two different routes, but book and claim also works when you just have a single carrier who’s able to offer a zero emission route, a zero emission trucking service on one route but not another.
Book and claim in general solves many of the challenges I previously mentioned. It lets carriers deploy zero emission trucks for their most operationally efficient, maximizes vehicle and infrastructure utilization, and because buyers are willing to commit to purchasing ZETcs rather than moving their physical freight on zero emission trucks, they’re more comfortable with longer multi-year contracts, as we saw through our pilot procurement. Together, these factors make projects more economical and feasible.
GMA Trucking goes beyond establishing a book and claim system. We also operate a buyers alliance for companies interested in purchasing the ZETcs, acting as demand aggregators. Coordinated demand sends a strong market signal that there’s real appetite for zero-emission trucking services. Companies in the alliance also get better deal terms because they’re going to the market as part of a larger project than individually, and the alliance facilitates peer-to-peer learning, with members knowing that the environmental attributes that they purchased meet strict environmental integrity standards.
Now that we’ve discussed how book and claim and demand aggregation can be a solution to decarbonizing the trucking sector, I also want to talk about GMA’s pilot procurement for ZETcs in more detail. I just want to note that while we are striving to share as much as possible about this procurement, we are unable to share confidential data such as pricing and specific contract details.
But getting to it, in late 2024, GMA Trucking pulled demand from its members and launched a competitive procurement for zero-emission trucking attributes. The RFP gave carriers about four months to work with truck manufacturers and charging providers to put together proposals. We asked for a variety of information, including the price per unit of activity in 10 kilometers, average payload, and financial and operating history. Because the procurement was going to use a book and claim system, we allowed projects to be anywhere in the continental US. They didn’t actually have to match our members’ actual shipping routes, which gets back to the geographic flexibility that I mentioned previously.
We did set additional guardrails as well. Carriers had to use class 8 battery electric trucks backed by renewable electricity or fuel cell trucks that met the strictest 45V tax credit requirements. Emission reductions also had to exceed legal requirements, adhering to the principle of regulatory surplus.
Overall, we were thrilled with the response, so we received 36 proposals from 9 carriers covering 14 states and representing 1,400 million ton kilometers of potential zero-emission trucking services. Overwhelmingly, 95% of the proposals had carriers choosing battery electric over hydrogen fuel cell. This wasn’t totally surprising to us, and we believe this reflects the market trends more broadly, where improving batteries, falling prices, and growing uncertainty around hydrogen policy kind of led carriers to that decision.
What did surprise us was the geographic spread. We got competitive bids well beyond California, where we expected the most to come from due to infrastructure and supportive policies that typically make zero emission projects easier. Carriers also submitted strong proposals for Pacific Northwest, the Mid-Atlantic, and some routes along the I-10 corridor.
In May 2025, we began evaluating these proposals, and after some follow-ups with carriers, we shortlisted the bids based on a list of criteria, among them being the price per attribute, how well the volume aligned with our member demand, and the overall bid quality. This shortlisting included carrier interviews to gather more information and an in-depth due diligence process that we conducted with a third-party consultant. We believe that the end responses that we got, especially those last three bids, were really solid, and from those 36 bids, we narrowed to three finalists before selecting our final winner.
With that, in September 2025, after months of review and discussion, GMA Trucking announced Nevoya as the winner of our pilot procurement. Nevoya is set to deploy 40 brand new class 8 battery electric vehicles on a route between Dallas and Houston, the largest known deployment of zero emission trucks in Texas.
To put this number into even more context, remember that the first half of 2025 only saw 200 electric trucks that were sold. So these 40 trucks that one carrier, Nevoya, is about to put on the road equates to 20% of what was done all across the country over the course of six months. That is a huge achievement. We are absolutely thrilled with our selection and have the utmost confidence in the success of this project.
After the announcement in September, GMA Trucking and Nevoya began the process of drafting a template contract for members. The contracts our members sign are bilateral, meaning that they’re between the buyer and Nevoya. Though GMA coordinates alignment on key terms and preferences, facilitated discussions between Nevoya and members, and played the role as coordinator. Even throughout that, we are not signatories to the contracts ourselves.
So I do want to highlight again, like these are bilateral contracts just between the buyer and Nevoya. Some of the innovative terms that we negotiated on behalf of our members include payment upon delivery of the ZETcs, which protect members from underperformance risk, multi-year contracts to give Nevoya demand certainty, tiered pricing to guarantee members the lowest price possible, and the option to extend at a discount.
We’re really excited about the novelty of this contract, even compared to the other procurements GMA Trucking has, or GMA has run in other sectors.
With all that said, I am so pleased to introduce JV, the Chief Commercial Officer and co-founder of Nevoya, to share some words on what winning the GMA’s pilot procurement means for them.
JOHN “JV” VERDON:
Stacey, thank you so much for that introduction. I very much appreciate it.
So as Stacey mentions, Nevoya is fully electric truckload carrier and it now focuses making zero emissions freight seamless and cost competitive for shippers and 3PLs. Currently running about 30 trucks across over the road and drayage operations in California, Texas, and Arizona. As Stacey mentioned, incredibly excited to be deploying 40 trucks between Dallas and Houston as part of the GMA RFP here.
So I think it was worth talking through a little bit more about Nevoya, and then I’ll give some perspective and feedback on how it was working with the team as part of this RFP, and then a little bit more on why it’s so important for helping us accelerate the transition to electric freight.
I’m assuming most people on this call do have that fundamental belief in the long-term economics of electric trucking, but one of the things that we’re sort of increasingly seeing is that electric operations require demand purpose-built technology. Achieving the asset utilization rates in order to drive the cost competitiveness with diesel is going to mean understanding charging optimization, range prediction, and efficiency training, having that directly integrated in your day-to-day operation.
One of the things that we’ve built out ourselves has been an AI and EV-native transportation management system that is very much purpose-built to account for those unique constraints that come with electric trucks. Whether it’s the range, the charging logistics, the state of charge, and how do you think through integrating AI into the workflow of your dispatch and day-to-day such that the team can really lean into driving a high level of utilization.
Now, I share that to say that, and it would be remiss of me not to acknowledge that we operate in this world of constraints right now. So trucks are more expensive, the battery range is more limited, and charging infrastructure isn’t yet prevalent across the country. So I think it is easy for us all to sit here in a sort of a pessimistic and cynical manner about these realities.
Alternatively, the approach that we’ve taken at Nevoya and very thankfully we’ve started to see both in terms of the GMA, the GMA members and the industry at large, there is an opportunity here to lean into that focused can-do attitude and approach that I’ve spoken about in the past. We want to work with partners in the industry to find the solutions that customers want and need. That could be us figuring out how to deliver direct freight capacity in certain markets, or it could be in the establishment of this wonderful book and claim program for trucking.
Both Andre and Stacey mentioned how book and claim mechanisms are already gaining traction in other sectors, whether it’s the sustainable aviation fuel space, the maritime space, and major shippers are looking to use those as tools to drive their decarbonization agendas. For us, it’s incredibly exciting to work with the GMA to establish both the operational and the commercial framework here for book and claim in the trucking industry. It kind of sets that stage for the future.
Stacey also did a really good job of talking through the RFP process more generally. I think you can all attest to the fact that it was incredibly rigorous, collaborative, and in fact, this is first of kind and is market defining. So again, really excited to partner and work with the GMA on establishing that foundation, setting the stage for the future and the ability to go even bigger as time progresses.
From our perspective, the RFP process forced carriers to think pretty systemically. Whether it was the TCO modeling, whether it was the infrastructure planning, understanding the sustainability compliance, and the book and claim architecture in an integrated fashion, we had to really, really dig deep. Worth mentioning that we had two full-time employees working on the RFP for three to six months, building a strong sense and understanding of how can this be a tool for us to catalyze and accelerate the transition to electric freight.
I think what set us apart was that systems level approach. I don’t think we just showed feasibility. We worked to demonstrate sort of simulation validated network design, integrated infrastructure planning, and also digging into what does the data architecture and infrastructure need to look like in order to capture the verifiable data that demonstrates the integrity and the trustworthiness of this program. Crucial that as we go to market with this, we are giving all of the different stakeholders exactly what they need through this program.
For me, this was like a really great example of the importance of the ecosystem approach in solving this challenging problem. We’ve all got a part to play here and that must be baked in operational practicality. The engagement we had both with the GMA and then with the members really centered around like what does this real world deployment look like, not just theoretical concepts.
A couple of other nice call outs for me I’d have here would be we found that the team on a day-to-day basis were an incredible thought partner. Again, like we were creating contractual terms for the first time and understanding the nuance of that, how that mattered from a carrier perspective, how that would matter from a shipper perspective, how that could work from a 3PL perspective, and ultimately like what is the right way to approach that from a compliance and regulatory perspective. It wasn’t easy, but in hindsight, it was a lot of fun.
I have to express my own personal gratitude for the hard work over the holidays in particular. Getting these closed out within a three-month period is no mean feat.I know that I in particular was pretty demanding and pestering of a number of folks who are on this webinar. So personal gratitude on that. It was a genuine pleasure to work getting this up and running.
Other things to say is I think there are from a values perspective, like we were very much aligned. So at the get-go, making sure that we all understood the simple things around being a catalyst for change, having this ability to build in public and share the information with the industry at large, incredibly important to all parties.
But also around like some of the regulatory components, whether it’s additionality, the credibility of the accounting, leaning into the MBM framework, and also just making sure on a day-to-day basis, the way in which we would communicate with the members, the GMA, and those other stakeholders who were involved, incredibly transparent and with a high level of integrity, meaning that when there were challenging conversations around contractual terms, everybody was on the same page. I think that combination and that willingness to step up to the plate and work together was the thing that got this all over the line.
Last couple of comments from me around the importance of book and claim as a tool. From a carrier perspective, it’s abundantly clear that book and claim is a tool that can unlock the scale at which you’re delivering the zero emissions freight. For us, this is this perfect example of deploying 40 trucks in the Texas market, capital formation is typically a challenge here. If you think about the upfront capital expenditure for trucks, charging infrastructure, that can be pretty prohibitive when you are looking to build a network in the new market. For us, having that committed revenue over a four-year period via this GMA RFP program massively de-risks the deployment. It enables the financing of the trucks. It helps facilitate the underwriting of the infrastructure built out, and that ultimately allows us to expand into new markets where customer freight density is still building from an EV perspective. So hugely important in our understanding of how that capital formation comes together and our ability to serve in a market ahead of time.
Another component that is often talked about, and rightfully so, is the TCO piece. The book and claim program here really accelerates that path to cost parity. As I mentioned, EVs have the higher capital expenditure, but a lower operating expenditure, so you need the utilization and the infrastructure efficiency to reach that TCO parity with diesel.
That problem, in order to hit those, like book and claim lets us really front load those investments that drive that efficiency. We can focus and deploy optimal charging locations from day one. We can deploy a larger number of trucks, which means better charger utilization and therefore a lower per truck infrastructure cost. Then we can also go through the process of really refining the operational model such that we are pulling forward that time period of driving to cost parity.
The final piece I’ll mention around is around the network economics. I think a unique piece here is EV deployments in general can be pretty challenging because it is tough to find the return trips in an efficient manner. So what we have here is this ability to fill back hauls at diesel rates in markets where there is the density of freight because the environmental attributes are decoupled and sold separately.
So that ability to spread more ton miles of activity lowers the cost per certificate and can be more, and enables us to be more competitive from a direct procurement, effectively enable us to serve shippers with a variety of solutions.
I’ll wrap it up there and hope that gave a useful carrier perspective as to the why. But again, like massive gratitude to all of the folks involved in the program. It was, it’s been a wild ride, but it’s been incredibly fun working with you all. Thank you. Passing it over to Clayton, I believe.
CLAYTON GERBER:
Awesome. Thanks so much, Dave. We really appreciate it and really helpful to hear your insights. Just want to share my own gratitude to you and the rest of the team. It’s been a pleasure getting to work with you all through this point. I’m excited to continue that work.
I’m just going to take a few minutes here and walk through some of the things that we’ve learned. Other folks on the call today have noted a few of those things, but I’m just going to step a little bit deeper and kind of make sure that y’all are taking away some of the real insights that we see.
At a high level, just quick summary, this procurement was really valuable to us in this nascent market as we look to expand and scale in the future. JV noted on a few of these things, but really the impact of book and claim on that increased utilization of the vehicles, also the power of demand aggregation and that increased demand on enabling charger maximization and decreasing costs over more assets and more operations. The impact that longer contract duration has on lowering the price per mile or price per certificate.
Then also, the innovative commercial structure really demonstrates the way that we can align incentives for future projects to be able to make sure that both the demand and the supply are comfortable in reaching that financial approval to be able to go through with these kinds of investments or partnerships.
Then lastly, the role that demand aggregation in a central node can play in aligning commercial terms over a number of different buyers and shippers in this case, the way that played a really catalytic component in keeping those contracting conversations organized and streamlined.
So stepping into the first one, JV mentioned this a little bit, but visually demonstrating the impact that truck utilization has on the overall TCO. This is a simplified illustrative graph on the right here, just demonstrating that the battery electric trucks have that higher capital costs for both the assets as well as the chargers and the infrastructure compared to diesel. But when we look at the operating costs, those are lower typically in most geographies than that of diesel. So the higher utilization gets you closer to that point of TCO parity.
What the RFP responses demonstrated is that many of the battery electric responses for existing trucks, or those that were already operating today, were for more often lower utilization trucks. That’s obviously a component of several different factors, both from the technical range capacity, but also the route planning constraints that they were under, as well as the ability to find carriers to help partner in that deployment. What we saw typically is that higher premiums were coming from those lower utilization, in particular those that were from existing trucks.
On the other hand, many of the trucks that were coming from net new operations could really see the impact of book and claim on the vehicle utilization to close the gap between the better electric and the diesel TCO. So by having that higher utilization, we can reap the benefits of that lower operating costs more extensively, and that will lead to the lower green premium and amortizing costs over more miles, spreading that out over more miles and therefore emissions impacts.
On the second insight here around the charger maximization, so just quickly demonstrating that outside of the truck expense, obviously charging infrastructure is a critical component and a critical expense. So what we see typically is that when charging infrastructure is deployed, they may not have full assurance on the utilization of those chargers. Typically then we can see a higher price.
What the RFPs showed is that with a lower amount of demand, we’re going to have a higher price per charger or per charging infrastructure site per truck, and therefore a higher relative cost. When we look at the higher demand that we could bring and we can flex up some of the procurement, excuse me, some of the responses, we could see that would lead to lower per unit costs for the charging and therefore decrease the overall green premium or the overall ZETc price. So the RFP was a really valuable insight into actually having the cost economics and data to be able to demonstrate this impact in a really real way tagged to specific projects.
The next one is around that contract length. What we demonstrated both from the RFP itself and the responses, but also kind of all the preceding conversations is that there’s generally a reluctance to go through longer term contracts for direct shipping engagements with carriers. That’s due to a number of very legitimate business changes and operations and risks that may happen to shippers.
What the cause of that from trying to deploy battery electric trucks and infrastructure is that carriers are typically more interested in concentrating a higher proportion of the CapEx premiums into that shorter duration of contract because they’re not confident or not necessarily contractually assured that they will be able to recoup more of those costs after that contract. So we can see a disproportionate amount of that coming in and therefore a higher premium.
When we’re able to more flexibly have a longer contract that’s really enabled by that book and claim chain of custody model, we can see that therefore the charger premium and the vehicle premiums are spread over more years and that means more miles. What that then ultimately results in is a lower cost, a lower marginal cost of green miles or green emissions, emissions abatement.
Therefore, this is really a catalytic component to the book and claim system, being able to really more readily allow organizations and more comfortably allow organizations to engage in this market for longer term contracts. Many of the companies that we’re procuring through this RFP are comfortable or may be going through other kinds of long-term contracts, such as power purchase agreements that look different, obviously, than typical logistics contracts. But there may have team members who are able to leverage some of their expertise across different sectors to understand what are these contracts look like and how might this benefit them.
The next one is around the commercial model here and the pricing. So as I said, I’m not going to share anything more detailed than this around any specific pricing. But this was one of the, I’d say, most complex of the contracts that we’ve engaged in GMA because of the forward-looking nature of it. These trucks are not yet in operation, but they will be. So we had to be able to bridge the gap of incentives across the different parties as well as the risk exposure. So we needed to work with our members and Nevoya to be able to come up with the right pricing and commercial model here.
So a couple of the components I wanted to highlight are these are payment upon delivery of the ZETcs. What that means is as the trucks will actually be operated on a recurring basis, then once they actually move, that is only what the buyers will contribute to and be able to transfer. There’s no ex ante component of this from an either emissions accounting or a payment perspective.
The next is around tier pricing. What we did here is we’re trying to balance the incentives from the carrier side and the shipper side on making sure that there’s no payment for things that they’re not actually being able to receive or that the carrier is not left with a significant portion or component of the green premiums without the ability per their contract to be able to actually contribute and buy down those premiums. What we did is we looked at having kind of a higher price for a tranche of those TKM, or ton kilometer of ZETc, and then that price steps down as they utilize the vehicles more.
The last component here was kind of an option. This is something that gave our members a bit more confidence and comfortability and being able to know that this is like an early access. They have an access here to be able to purchase more ZETcs as the vehicles may live longer than the contract duration. So they have the option of having an extension here.
All these things combined really are this innovative approach to the commercial model allowed the buyers and members to get comfortable as well as for Nevoya to get comfortable with this kind of model. So really taught us the value of commercial, definitely worked really hard with the team to be able to come up with this approach.
The last thing that’s very connected to those terms I just mentioned is the nature of a central node in these conversations. As we said, the contracts are signed bilaterally across the buyers, and in this case, Nevoya. But being able to organize all these different preferences, all these different terms, into the central player of the GMA Trucking team and then in coordination to have those direct early stage conversations with Nevoya significantly streamlined the process for us because we couldn’t have every single member negotiating separately with Nevoya without some sort of commonality and through line to help really make sure that there was efficiency in this process.
What we really learned is that this was a critical component of this broad demand aggregation. Without it, there may have been deviations that could have put the project at risk.
So really, really appreciate both the partnership from Nevoya in these conversations, from our lawyers, and also obviously all of the buyers that were involved in this, which was a really collaborative process. It was really great to see everybody coming together and being able to help shepherd through this really innovative approach.
So with that, I am excited to introduce the two shippers that we will hear from, both from Amazon and Etsy. So with that, perhaps I’ll hand it over to Eleanor if you want to share a few words about what this process meant for you and any reflections you have.
ELEANOR BASTIAN:
Thank you, Clayton. And thanks for hosting this webinar. It’s great to have this out here. I’m glad you’ll have a recording because you’ve really shared so much specifics about what we’ve developed over the last year or so, and I hope it’s really valuable to everyone here. And thanks for joining.
I’m Eleanor. I’m with Amazon. I work in worldwide operations sustainability. What I’d like to share is that sort of as GMA covered at the beginning, at Amazon, we see the utility of book and claim in a lot of different spaces. You can look at it as hard to abate or just nascent supply chains or high initial costs. But when it’s difficult to directly procure, consume a low carbon solution, such as for electric trucks, as well as building materials like steel and concrete and fuels like sustainable aviation fuel and renewable diesel,book and claim mechanisms, we think, can really advance decarbonization, provided that they are designed with clear rules, terms, and conditions that are high integrity.
So that’s what we created here with GMA Trucking, and we’re really proud to be part of this today and discuss it with everyone. What we see that book and claim did here was provide producers with a set of buyers without creating these issues for truck utilization. Then it, in a very seamless way, gives the buyers like Amazon the ability to make these credible and verifiable environmental claims that can go towards our climate goals.
What we have seen over the last few years is that it’s really hard for carriers to adopt electric trucks when they have a lot of different customers or shippers because they have this sort of ad hoc interest from all their shippers that’s not really, it’s a lot of different lanes, a lot of different times of the year, et cetera. That can just destroy your vehicle utilization or the number of miles you drive on a vehicle a year. That utilization is how you manage your total cost of ownership and principally.
This whole approach that they’ve described in detail today avoids that whole challenge because we’re separating out this benefit from going and getting loads that work for that vehicle on a daily basis. So you’re getting the maximum amount of miles per year.
I’ll just say one more thing that there’s a lot of different types of buyers that were involved here. Amazon is a little different because we are a carrier. We own trucks. We are a shipper. We are sort of a freight forwarder. We buy a lot of fuel. We work with OEMs. One thing that’s really cool here that’s different from other market-based mechanisms is that within a year or so, we may be able to physically procure truckloads from Nevoya in Texas, and have this combination of a market-based solution with EACs as well as, they’re just running our loads with the volumes that we have in Texas, which are pretty significant.
So I can say a little more about what my feedback is in the process, maybe after we hear from the other buyer.
But I just wanted to say now that Amazon is really proud to work with the Center for Green Market Activation on this initiative and other initiatives and really proud to work with Nevoya as well. So thank you to Clayton, Stacy, Andre, JV, and Sam.
CLAYTON GERBER:
Awesome. Thanks. Thanks so much for that. I really, really appreciate it. And it’s been a pleasure working with you as well. Sam, I’ll turn it over to you for a few words as well.
SAM BRUNDRETT:
Yeah, thanks, Clayton. Hi, everyone. I’m excited to participate in today’s call and help announce the launch of this pilot.
My name is Sam Brundrett, and I’m the Environmental Impact Lead at Etsy. A little about our business and our decarbonization journey that I think will help write context.
We operate two global two-sided marketplaces, Etsy.com and Teapot. These marketplaces connect with millions of buyers and sellers around the world. We don’t own inventory. Instead, we facilitate shipping by negotiating rates with carriers like USPS, UPS, FedEx, a bunch of others, and we offer those shipping labels to sellers.
Through this process, we facilitate hundreds of millions of parcel shipments each year that travel through a network of consolidated along all middle mile and last mile transport modes. Shipping is therefore super important for our climate strategy. We have an SBTi-approved net zero goal that includes all of the emissions that we facilitate through our marketplaces, and it’s about 60% of our total footprint, or about 300,000 metric tons of CO2. The majority of that is coming from ground transport.
Historically, our decarbonization levers have included enabling local commerce through search and filters on our platforms, advocacy, and carrier engagement and selection. But because sellers ultimately have or choose the carrier and shipping methods, our ability to directly influence emissions reductions have been somewhat limited.
This is why we see book and claim as such an important and complementary solution, provides credible, scalable way to support zero emissions trucking in regions where our shipping volumes are pretty high, but where access to physical electric trucking services remains somewhat limited or non-existent.
It also allows us to help accelerate the deployment of these solutions today rather than waiting for their availability in the future.
Lastly, I’ll just say we’re particularly excited about this project because Etsy has millions of buyers and sellers in Texas. It’s a big market for us. So supporting cleaner freight in this region improves reliability of shipping ecosystem and delivers local air quality benefits to communities.
Through the book and claim approach, we plan to apply these certificates towards progress on our net zero goals, using frameworks like the AIM standard, as well as the Task Force for Climate Action Transparency, or TCAT, while helping inform the updates to the SBTi and GSU protocol standards related to use of market-based mechanisms in scope 3 over the next month, two months to a year.
Just thank you very much to the GMA folks. As Eleanor said, they have done just such an amazing job of shepherding the initiative from program design, running the RFP, and supporting the contract development process, which I know just sounds so banal and boring, but it is just like such a painful process for anybody who’s been on either side of that process. So to have support there is really instrumental, as well as obviously looking forward to participating or partnering with Nevoya and continuing to learn from their GMA trucking buyers.
So with that, I’ll pass it back to Clayton.
CLAYTON GERBER:
Awesome. Well, thank you. Thank you both. Really, again, it’s been a pleasure working with you and all the buyers, and thank you for sharing the words on this webinar today. It’s really helpful, I think, to have folks hear from you directly to be able to really share the insights and learnings and learn how to get involved. So thank you.
In the last couple of minutes here before we turn over to Q&A, and we’re right on time, which is awesome. I just want to make a couple of different announcements on what is coming next for us and what we’re continuing to explore for 2026 and how to get involved.
So building on these lessons learned, we are looking to explore another concept here, which is more intentionally trying to pair together the book and claim concept with the physical demand that’s more traditional in the market to bring these two things together to lower overall economics and increase that utilization, as we’ve been talking about a lot today, to be able to move towards that future state where physical demand is kind of all we need.
One of the things I’ll note that we haven’t mentioned yet today is especially in this sector, but across all our sectors, but especially in this one, we don’t see book and claim as the 2050 target necessarily. We do hope to see a world where the total cost of ownership and the cost of these assets, as well as the charging, are ubiquitously available across the US and ideally around the globe at some point so that a shipper can say, “Hey, we want electric or battery electric services, please provide that carrier.” And they can actually do so.
But right now we need to bridge the gap and we need to accelerate the market as fast as possible. So another thing we’re going to be exploring this year is can we integrate these two things to try and bring kind of the power of both of them to that solid physical demand as well as that flexibility of book and claim. That would hopefully increase the utilization of those vehicles, again, further decrease the cost of chargers by increased utilization. And then again, allow that optimization for both charging and route planning.
We also will be exploring doing another pure play version like we did last year, but we’ll kind of depend on the overall demand that we have and the different project scoping that we’re going through now. So very excited for what is to come next.
Last thing I’ll just say just a little bit about GMA Trucking. So we are, as I said, a membership organization of those buyers, bringing them together to be able to have the demand aggregation function. That includes both the shippers as well as freight forwarders who are looking to address emissions within their scope 3 primarily. We also work, really, membership is global, but we focused this last on the US. We are looking to expand in the coming years, and then there are discounts available for having different memberships across the different GMA programs.
Then the last thing I’ll note is that commitment and involvement provides a lot more than just the RFP. There’s a lot of shared learning, influence into the system and the decisions we make. So actually members are not required to join in their procurement. We don’t ask for a commitment up front. Obviously we want folks to be involved, but it’s not a commitment just to join, and any decision on buying or participating in the RFP can come later.
But we also, it’s not just on the shipper side. We do a lot of engagement with every intermediary and every part of the value chain, whether that be CPOs, carriers, freight forwarders. We really want and need to learn from the market and get everybody involved to be able to have this process scale in the future.
So we are always looking for folks to speak with. You can reach out to us at the trucking@gmacenter.org e-mail or reach out on LinkedIn, our website, anything else like that.
I’ll also note that we will be publishing a white paper in the coming weeks that we’ll go through in more detail some of the different things that we talked about today so that you can review and ask if there’s any other questions. And hopefully that’s a helpful resource to you all.
So with that, we have about 5 or 6 minutes left.
I want to just open it up, Sam, if you could help, GMA Sam. It’s confusing to have multiple Sams on the team, but if you could help shepherd us through some questions here, I’m happy to answer some, and for those that we don’t answer, we will look to try and provide some responses after the call.
SAM PEARL SCHWARTZ:
Yeah, thanks, Clayton. And we’ve had some great questions come in over the chat. So as Clayton mentioned, I don’t think we’ll get to all of them right now, but we’ll get through it. We can over the next 6 minutes and follow up if necessary.
Clayton, maybe I’ll stick with you. We’ve got two questions related to verification and registry, kind of interrelated topics.
So kind of a first question on how are these certificates being certified or verified and then connected to that once they’ve been certified or verified, is there going to be a registry by which these attributes are being tracked?
CLAYTON GERBER:
Yeah, happy to speak to some of that. So they definitely are verified and they’re going to be following the GLEC framework from accounting. So as we talked about earlier, the functional unit here is the emissions intensity of the activity of the service. So that’s going to be looking at the emissions per ton kilometer in this case, following the GLEC or ISO 14083, and then they will be verified by an accredited third party to ensure that all the data going into that calculation is accurate and robust.
Then from a registry perspective, we’ve been working over the last, through this RFP and continuing to finalize exactly what the registry provider will be, but we are looking to partner with one of the existing providers in the registry space. It’s critical to us that certificates are tracked and transparent, and so it’s a really needed component to have this be logged and tracked on a registry.
I’ll also just note quickly, I think there was another question in this, in here, and we kind of sped over the timeline. The trucks are looking to be deployed and actually operational by the end of this year or early next year, and so there is some time here to kind of flesh out some of those details. But absolutely, the accounting is a critical point, as is the verification and the registry.
SAM PEARL SCHWARTZ:
Thanks, Clayton. I’m going to actually stick with you related to accounting.
We had a question on more details on the energy source that’s powering the EVs and more specifically, how are you and how are we calculating the kind of emissions profile of that service?
CLAYTON GERBER:
Yeah, absolutely. So again, in alignment with the GLEC framework and ISO 14083, you will be looking at the energy used for that service. So in this case, for battery electric, that’s going to be the kilowatt hours. So for each kilowatt hour dispense, there’s a whole methodology involved in that standard around what do you do about any losses in the charging infrastructure and what data sources are available.
So we’ve worked with the participants in this process to establish the verification document to be able to ensure that there are credible and most primary data as possible. We really want to focus on having primary data as opposed to any sort of model data.
Again, per the ISO 14083, we will report both the location based, but as a requirement for this process, we want to make sure that we’re backed by renewables. So we require the purchase of Green-E eligible RECs as well to be able to be able to address the emissions coming from the electricity because it’s not just at the wheel, it’s also the well to tank part as well.
So we will have RECs being backed by them and then those will also be sourced from Texas. JV, I’m not sure if there’s anything else you want to share there, if that captures it.
JOHN “JV” VERDON:
I think you captured it really nicely there, Clayton.
CLAYTON GERBER:
Cool.
SAM PEARL SCHWARTZ:
Awesome. Thanks, Clayton. Well, I know we only have two minutes left, so maybe we’ll answer one final question. I’ll note we’ve gotten a bunch of additional questions in the chat since we started the Q&A. So I want to reiterate, we’ll try to address those that we can after the close. Andre, maybe I’ll turn to you just to close.
We had a kind of question about how we see this program scaling and the opportunities for scale, the opportunities for kind of reducing friction points and expanding the scale over time.
ANDRE DE FONTAINE:
Yeah, thanks, Sam, and thanks for the question. I mean, that’s– a big part of what we’re focused on is, how do we take this to the next step? And when you look across our, the programs that the GMA has been involved in over the years, they do follow a similar trajectory where you do an initial pilot, sometimes small scale.
In this case, it’s still pretty significant, and then that proves out the concept. A lot of the communications that go around the results end up drawing more participants in. So part of this is a question for those of you on the call. How can you help us by getting involved and spreading the word?
But we are looking ahead to our next effort. Clayton mentioned combining physical with book and claim, which we think holds a lot of potential. And a lot of our ability to scale, yes, it’s about drawing in more participants, but it also is around standardizing aspects of the process. We learned a huge amount through the contracting. We think it’s going to be a lot easier next time we do this, we think things will be a little bit simpler. Once we’ve got an established registry partner, there’s a lot on the accounting side that we had to work through.
Then just the RFP process itself, I think, can be streamlined along with how we think about pricing. Some of this we do plan to publish.
I think there was a question there about, will we be releasing templates? Yes, we will be doing that. I don’t know exactly which elements we’re going to templatize, but that’s certainly part of the plan to make at a minimum those documents available to our trucking members and then some also to the general public.
I will note alongside this, we are developing a white paper that goes a bit deeper on a lot of the issues that we talked about today, which we will be releasing over the next few weeks, so that’s something that we would encourage everybody to take a look at. I think they’re the insights that we draw out of that process will help us scale to the next steps.
So with that, I think we are right at time. So Sam, should I just close this out now that I’m talking? Okay, great.
Well, thank you so much to all of our speakers today who did such a great job explaining this complex initiative. And thank you to all the folks that took the time out of your day to hear about this.
Please don’t hesitate to reach out. I know that we weren’t able to answer all of the questions and there’s a lot of good ones that we weren’t able to get to. The team is here. We’re always ready to engage with folks productively. So don’t hesitate to reach out and there will be more to come on this issue as we continue to move forward.
So thanks so much. We’ll talk again soon. Thanks, everybody.
Related News & Resources
01.15.26
First Ever GMA Trucking Procurement Brings Together Leading Companies to Enable Largest Known Deployment of Class 8 Battery Electric Trucks in Texas
Results from the first-of-its-kind pilot procurement show that a market-based approach can effectively accelerate deep decarbonization in heavy-duty trucking.
Washington, D.C. – January 15, 2026
In a major milestone for electric freight, the Center for Green Market Activation (GMA), in collaboration with strategic partner Smart Freight Centre (SFC), announced the results of its groundbreaking pilot procurement that will enable the largest known deployment of Class 8 zero-emission trucks1 and associated charging infrastructure in Texas. Leveraging corporate demand for decarbonized on-road shipping from first mover companies like Amazon, eBay, Etsy, Green Worldwide Shipping, and Meta, the program will support carrier Nevoya in deploying roughly 40 Class 8 battery electric trucks on a new all-electric Houston-Dallas route.
The trucks are expected to travel up to 7 million miles annually, reducing an estimated 60,000 metric tonnes of CO₂e, improving local air quality, and decreasing noise pollution. Through multiyear offtake agreements, participating companies will receive verified zero-emission trucking service attribute certificates as early as 2026, accelerating Nevoya’s fleet expansion and advancing decarbonization within heavy-duty transport.
“With this pilot procurement, GMA Trucking has shown how to translate market demand for zero-emission trucking services into scalable deployments,” said Kim Carnahan, CEO at GMA. “Through a competitive procurement process and advance purchase commitments from leading corporations, we’ve proven a replicable model to get urgently needed zero-emission trucks on the road. With contracts signed, we’re already planning for our next, even bigger procurement.”
While many shippers are committed to decarbonization, less than 1% of new heavy-duty vehicles in the United States are electric2 and companies struggle to find available zero-emission services on their routes. As the first large-scale application of book and claim to zero-emission trucking, the GMA pilot procurement tackles current EV access barriers and will enable Nevoya to deploy new trucks where they deliver the strongest commercial and operational value.
Similar to programs like the Sustainable Aviation Buyers Alliance (SABA) and the Zero Emission Maritime Buyers Alliance (ZEMBA), the GMA approach decouples the environmental benefit of the zero-emission trucking service from its physical delivery, allowing the environmental attributes to be sold and tracked separately. GMA Trucking members who purchase the attributes can claim the associated greenhouse gas reductions while helping grow the market for decarbonized trucking services.
“We’re thrilled to partner with GMA and Nevoya on this procurement,” said Sam Brundrett, Environmental Lead at Etsy, Inc. “This is an opportunity for an all-electric carrier to scale in a new location at a faster rate than otherwise possible. With millions of Etsy items moving through Texas each year, strengthening shipping reliability while cutting emissions and improving air quality for local sellers and buyers is essential.”
GMA Trucking’s book and claim system is built to promote accuracy, transparency, and credibility across the zero-emission trucking ecosystem. As Nevoya operates its vehicles between Dallas and Houston, an independent, accredited auditor will verify the environmental attributes being generated. These verified attributes will then be recorded in a registry, where they can be transferred to and retired by participating GMA Trucking members.
Charging will be fully backed by renewable electricity in the form of Green-e Renewable Energy Certificates (RECs).
“The advanced market commitments from GMA Trucking members represent a transformative moment—they’re not just supporting this deployment; they’re catalyzing a new model for how zero-emission trucking can scale,” said Sami Khan, CEO at Nevoya. “Book and claim helps unlock the capital and operational certainty to deploy electric capacity where it makes the most commercial sense, while our AI-native platform ensures we’re maximizing both utilization and emissions impact. Launching the Dallas to Houston lane is proof that the next era of trucking—combining zero-emission capacity, intelligent orchestration, and relentless efficiency—is already here.”
The GMA Trucking buyers alliance, launched in 2023 to accelerate the decarbonization of heavy-duty trucking, has grown to include nearly a dozen pioneering companies across technology, consumer goods, food and beverage, and other sectors who are ready to support action to address road freight emissions. This pilot establishes a model for future collective procurement efforts, helping to expand the deployment of Class 8 zero-emission vehicles into new regions while creating economically viable pathways for companies to invest directly in heavy-duty freight decarbonization. GMA Trucking is developing a second procurement, in partnership with SFC, that will combine book and claim with direct procurement of physical low-carbon trucking services for even greater scale and impact.
“Combining book and claim with direct procurement connects corporate climate commitments to real-world action, real trucks, real infrastructure, and real emissions reductions,” said Christoph Wolff, CEO of Smart Freight Centre. “This approach creates a scalable, credible pathway for decarbonizing freight.”
Companies interested in participating in future procurements or exploring membership in GMA Trucking can email trucking@gmacenter.org to learn more. GMA will also host a webinar at noon ET on Thursday, January 15 to provide an overview of the pilot procurement, share lessons learned, and discuss the road ahead – find out more and register here.
1 “Zero-emission trucks” refers to tailpipe emissions.
2 BloombergNEF & Smart Freight Centre. (2025). Zero-Emission Commercial Vehicles Accelerating the Transition. https://assets.bbhub.io/professional/sites/24/Zero-Emission-Commercial-Vehicles-Factbook-2025.pdf
Media inquiries please contact: Alison Greene, Communications Manager, alison.greene@gmacenter.org.
About the Center for Green Market Activation
The Center for Green Market Activation (GMA) is a US-based, globally focused non-profit. Through innovative procurement approaches and collaborative alliances, GMA catalyzes and scales the uptake of low-carbon goods and services within carbon-intensive industries such as aviation, maritime, trucking, cement and concrete, and chemicals. With collective decades of experience in environmental markets and alternative fuels and materials, the GMA team works to standardize new, green markets and forges mutually beneficial partnerships between climate-focused companies, suppliers, and mission-aligned non-profit organizations to channel funding to critical climate technologies in pursuit of accelerated sectoral decarbonization.
About Nevoya
Nevoya is the next-generation electric trucking carrier transforming American logistics through AI-native operations and customer-centric excellence. The company’s proprietary TMS platform optimizes vehicle utilization, routes, and energy consumption—proving that zero-emissions trucking delivers superior economics and service reliability compared to traditional diesel operations. By prioritizing efficiency, innovation, and deep customer understanding, Nevoya is establishing the new standard for freight excellence while accelerating America’s transition to sustainable logistics. Learn more at nevoya.com.
About Smart Freight Centre
Smart Freight Centre (SFC) is a globally active non-profit organization driving climate action in the freight sector. Its mission is to mobilize the global logistics ecosystem — particularly its members and partners — to track and reduce greenhouse gas emissions. SFC works to accelerate emissions reductions in line with 1.5°C pathways, aiming for a zero-emission global logistics sector by 2050 or earlier. Along the I-10 corridor, SFC has convened a shipper–carrier consortium to test and accelerate battery-electric truck adoption. For more information visit www.smartfreightcentre.org
Related News & Resources